One Integration Can Protect Margin Before Q4
Adding payment gateways often feels like the sensible move. A new ecommerce platform, overseas customers, telephone orders or a new payment method can each bring another provider into the mix. Before long, you are managing a payment estate that is harder to control than it first appears.
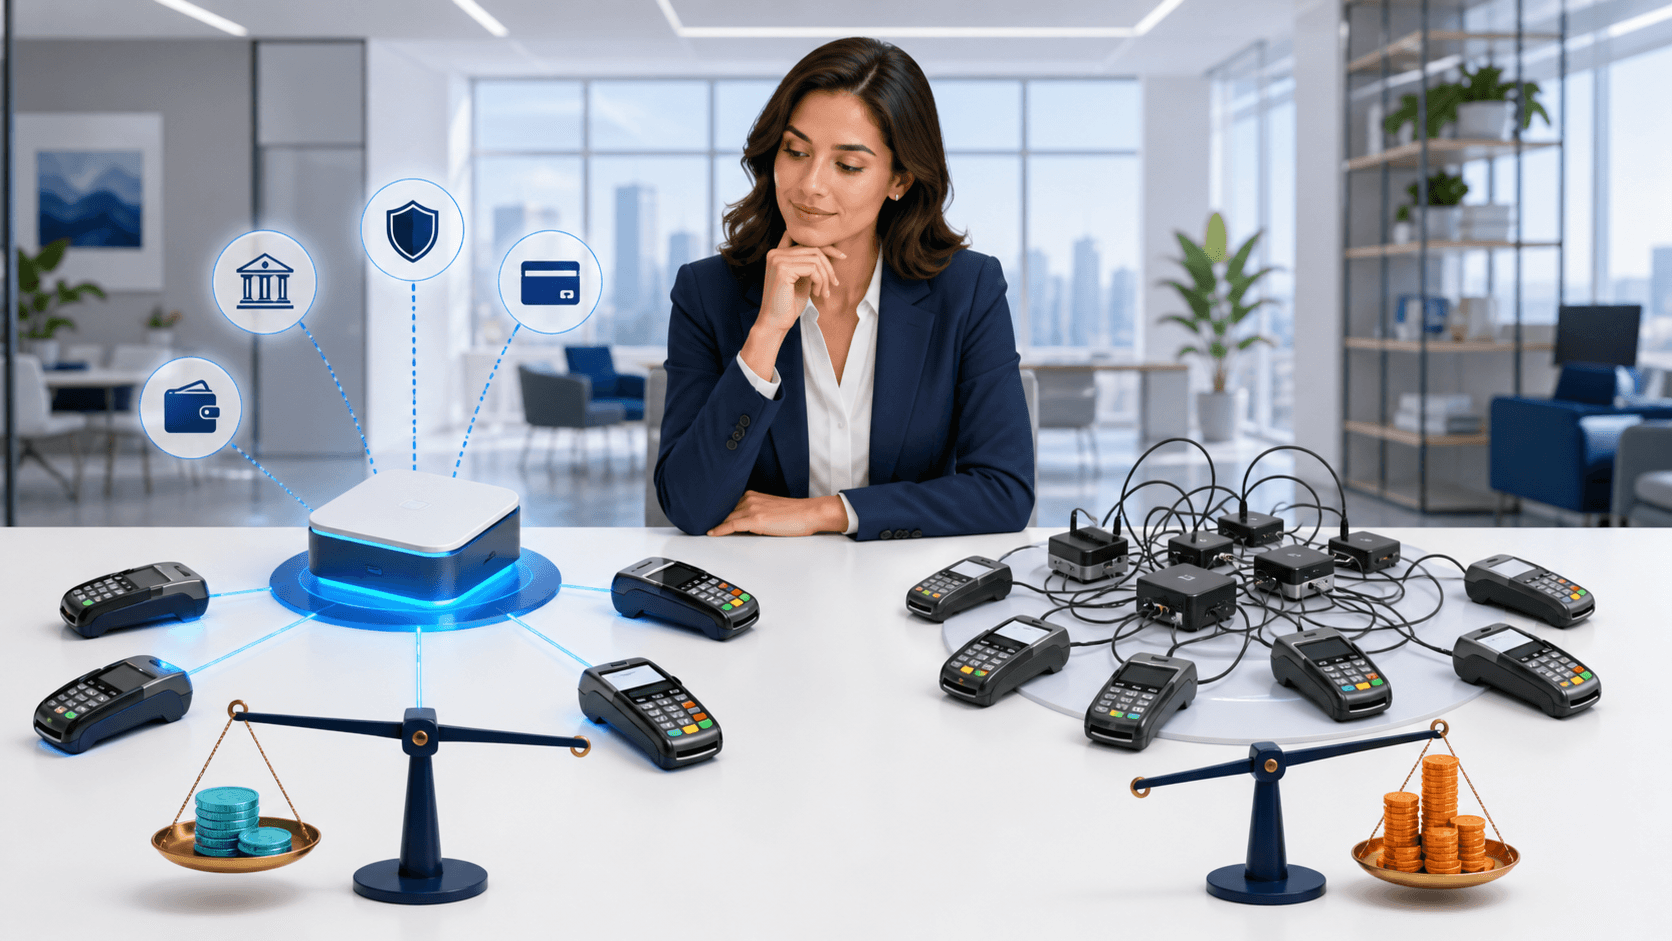
Each gateway may come with its own contract, monthly minimum, transaction fees, settlement timetable, support route, reporting format and security responsibilities. That fragmentation is not just an IT inconvenience. It can affect EBITDA, cash visibility and the time your finance team spends chasing answers.
September is the right point to review this before Black Friday, Christmas trading and year-end budgeting place more pressure on settlements and reconciliation. Unified payments can bring multiple payment methods into one operational layer, without removing choice at checkout. The aim is not consolidation for its own sake. It is to reduce avoidable friction, lower unit costs and give you a clearer view of cash.
When Gateway Sprawl Starts Eroding Margin
We recommend treating payment infrastructure as a finance and operations review, not simply a technology project. Growth can conceal waste. You may negotiate a better headline rate with one provider, yet still carry duplicate platform fees, separate integration support and higher charges elsewhere.
The warning signs are usually visible well before they appear clearly in the P&L:
- More than one gateway or acquirer contract with unclear ownership
- Finance teams exporting payment reports into spreadsheets each month
- Different settlement timings across online, telephone and in-person sales
- Payment failures, refunds and chargeback disputes managed in separate portals
- No reliable blended view of the effective cost per transaction
In a recent anonymised client review, a UK multi-site retailer used separate gateways for ecommerce, telephone orders and point-of-sale payments. Each channel worked well on its own, but the settlement data did not join up. Month-end reconciliation took longer, finance could not easily see the true cost of taking a payment, and management reporting became less reliable.
Contract renewal dates should trigger a review, but they are not the only prompt. Annual budgeting, acquiring another business, launching a new ecommerce platform, expanding internationally, adding subscriptions or preparing for peak trading are all moments when payment supplier arrangements need a closer look.
Multiple Gateways Carry Costs Beyond the Headline Rate
The advertised card rate is only one part of the payment decision. We encourage CFOs and finance directors to assess total cost of ownership across the full payment flow.
Direct costs can include gateway licences, transaction charges, acquiring rates, interchange fees, card scheme fees, currency conversion, refunds, chargeback administration and PCI compliance. Looking at one percentage rate in isolation can make a more expensive operating model appear attractive.
The less visible cost can be just as material. Reconciliation time, failed-payment investigations, duplicated supplier management, developer support, inconsistent reporting and settlement forecasting all add operating expenditure. A small manual task repeated across multiple channels soon becomes a recurring drain on the finance function.
Cash flow also deserves more attention than it often receives. Different gateways can settle on different cycles, making the daily cash position harder to forecast. Where margins are tight, delayed visibility can lead to unnecessary borrowing, missed supplier-payment opportunities and weaker working-capital planning.
Open banking can be a useful alternative for suitable payment journeys. Account-to-account payments can provide fast settlement, lower transaction fees in the right use cases and no card chargebacks. It will not replace cards everywhere, because customer preference, transaction value and checkout performance still matter. The benefit of unified payments is a consolidated view of fees, settlements and payment performance, so you can make those choices with better information.
Unified Payments Create Control Without Reducing Choice
One integration does not mean one way to pay. It means one operational layer that can support online checkout, payment links, recurring billing, virtual terminals, point-of-sale payments and account-to-account options.
That structure gives finance and operations teams a consistent reporting framework instead of a collection of portals, exports and manual workarounds. Payment status tracking, refunds, customer data handling and fraud monitoring can follow a clearer process. Just as importantly, connected data makes management information more dependable.
Conversion is part of the case too. Customers need payment options that work quickly and reliably, but you also need to know where payments fail and where people abandon checkout. When the data sits in disconnected systems, finding the source of revenue leakage becomes slower and more expensive.
In one anonymised client scenario, a UK service business taking deposits, recurring payments and ad hoc invoices was reconciling bank statements, accounting software and several gateway exports. Automated reconciliation and connected finance systems can remove much of that unnecessary handling.
Since 2016, our London and Essex team has combined FTSE 250-level buying leverage with practical systems integration experience. That means we assess the supplier arrangement and the operational fit together, rather than treating a payment contract as separate from the systems and teams that rely on it.
Build a Migration Plan Before Peak Trading Begins
A payment review should start with facts, not assumptions. Changing every flow at once is rarely necessary, particularly before a busy trading period. A phased plan can reduce risk while still delivering a clear business case.
- Map every gateway, acquirer, payment method, contract end date, settlement cycle, integration dependency and internal owner. Calculate the blended effective cost rather than relying on the card rate alone.
- Separate payment flows by customer journey. Ecommerce, in-person payments, invoices, subscriptions, deposits and high-value B2B transactions may each need a different mix of cards, direct debit, open banking or alternative methods.
- Model the financial impact. Include transaction costs, chargeback exposure, settlement timing, reconciliation labour, support needs and the effect on EBITDA and working capital.
- Plan implementation carefully. Confirm platform compatibility, data requirements, customer communications, testing, fallback arrangements and any restrictions around peak trading.
- Set governance after launch. Review authorisation rates, payment method adoption, failed payments, refund turnaround, chargeback ratios and effective transaction cost each month.
Turn Payment Complexity Into a Q4 Margin Gain
Payment fragmentation is often dismissed as a technical inconvenience. In reality, it can become a margin, cash flow and supplier-risk issue that grows quietly alongside revenue. The first step is not an immediate system replacement. It is a clear payment cost and operational review before Q4 volumes and year-end deadlines make change harder.
A sound unified payments approach should simplify administration without disrupting revenue collection or limiting customer choice. When you can see the full route from payment attempt to settlement, refund and reconciliation, you are in a far stronger position to protect margin during the busiest part of the year.
Lower Payment Costs Without Adding Complexity
Digital Media Technology Solutions can assess where fees, settlement delays and fragmented reporting are eroding margin across your payment estate. Our unified payments approach brings payment methods into a single, manageable framework while supporting lower transaction costs and stronger cash flow control. If you are reviewing processor contracts or planning next year's cost base, contact us for a commercial assessment of the opportunity.