Card Fees Are Quietly Draining Your Margin
Card acceptance is rarely just the merchant rate shown on a proposal. Interchange, card scheme fees, acquirer margin, terminal rental, gateway charges, chargeback administration and delayed settlement can all sit behind a single card payment. Together, they create a margin leak that is easy to miss until finance teams review the full P&L impact.
For owners, CFOs and operations directors, the problem grows with revenue. A small percentage applied to rising card sales can remove a meaningful amount from EBITDA, especially where transaction volumes are high and gross margins are tight. We help you assess whether open banking can lower transaction fees, speed up access to cleared funds and reduce dependence on card schemes, without disrupting the customer experience.
See the Full Cost Behind Every Card Payment
A card transaction passes through several parties before funds arrive in your account. Each may take a share or add a related cost. The headline rate may be only one part of what your business is actually paying.
Your payment cost stack can include:
- Interchange fees paid to the cardholder's issuing bank
- Card scheme assessment and processing fees
- Acquirer, processor and gateway mark-ups
- Terminal rental, PCI compliance activity and foreign exchange costs
- Chargeback handling, failed payment recovery and internal reconciliation time
Settlement delays deserve attention too. Money that is technically earned but not yet cleared cannot be used to pay suppliers, wages or other operating costs. Some providers also hold reserves, particularly where they see increased risk, refunds or disputes. Meanwhile, your finance team may spend hours matching settlements, fees and refunds across several portals.
Consider an illustrative business taking £5 million in annual card payments at a blended processing cost of 1.7%. That represents around £85,000 a year before terminal commitments, dispute work and finance administration are included. Actual figures vary by sector, card mix, average transaction value and contract terms, but the principle remains the same: payment acceptance is a supplier cost category. We believe it deserves the same scrutiny you would apply to energy, telecoms, insurance or shipping.
When Open Banking Becomes a Financial Priority
The right time to review payment economics is usually before a cost becomes embedded for another trading year. September is particularly useful because Q4 trading, annual budgeting and supplier negotiations are approaching. It gives you time to model the impact of lower transaction fees before card processing assumptions are carried into the next budget cycle.
We recommend a focused review when you see signals such as:
- A card processing contract renewal approaching
- Growing ecommerce or invoice payment volumes
- Pressure on EBITDA or working capital
- Rising chargeback ratios and payment disputes
- More manual reconciliation across payment providers
Open banking is often most relevant where payments are higher in value, repeatable or time-sensitive. This can include invoice settlement, account top-ups, deposits, bookings and ecommerce checkout. It can also be worth assessing where debit card volumes are rising, as account-to-account payments may reduce reliance on card rails and support faster settlement.
That does not mean replacing every card payment. Cards remain appropriate for many customer journeys. Our role is to identify the areas where an account-to-account option makes commercial sense, then measure its effect on conversion, cash flow and back-office effort.
Compare Card Schemes and Open Banking on the P&L
Card schemes involve multiple participants, including the issuing bank, scheme, acquirer and payment processor. Each layer can add cost, processing rules or operational work. Open banking payments use regulated payment initiation services to move funds directly from the customer's bank account to the business account.
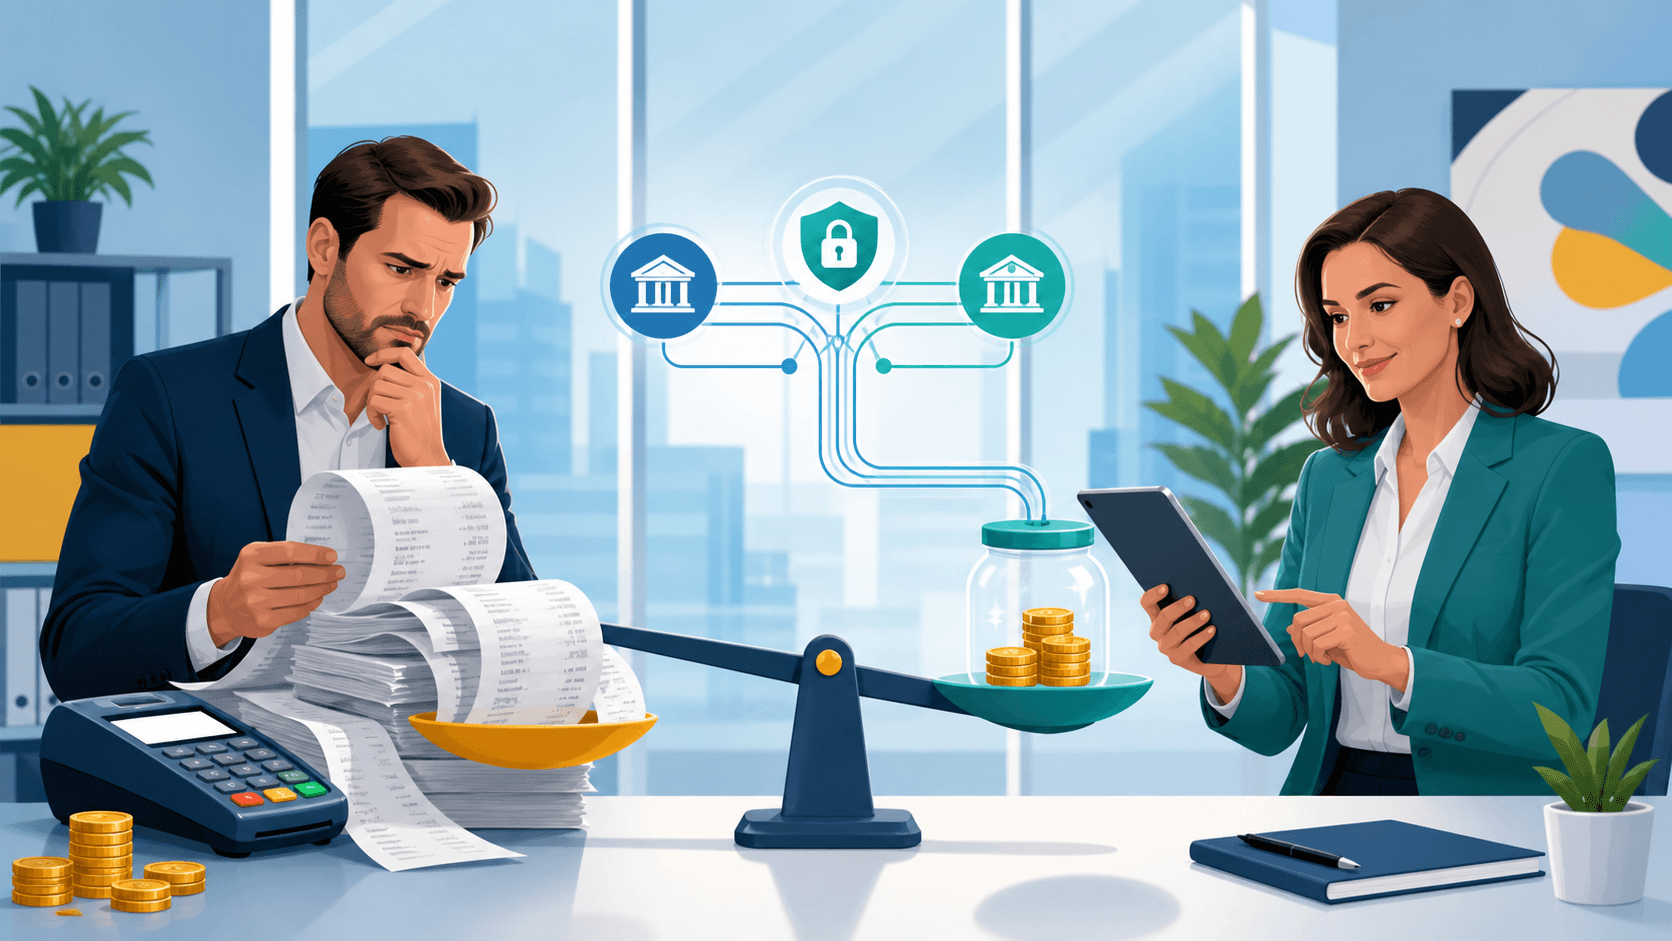
The difference can be material. As an illustration, moving £5 million of annual payment volume from a blended card cost of 1.7% to an open banking cost of 0.7% would create an indicative saving of £50,000 a year. This is not a pricing promise. We assess the actual payment mix, customer behaviour and supplier terms before making recommendations.
Open banking also changes the dispute picture. Card scheme chargebacks do not apply in the same way to account-to-account payments, which can reduce certain forms of dispute exposure. However, controls still matter. Clear payment references, refund procedures, customer support processes and fraud monitoring are needed to manage authorised push payment risk and maintain customer trust.
Integrated payment data can also remove friction inside finance. When payment records, refunds, settlement information and customer data sit in separate systems, reconciliation becomes slower and less reliable. Bringing those data points together can reduce manual administration and give your team a clearer view of cash received versus cash expected.
Build a Controlled Route to Lower Transaction Fees
Lower transaction fees should be the outcome of a disciplined payment review, not a rushed switch. We start by calculating the true cost of each payment method, including the direct fee and the operating work around it.
- Assess your current payment cost stack. A structured assessment should cover merchant statements, payment volumes and card types; average transaction value and settlement timing; chargeback ratios, refunds and failed payments; processor contracts, gateway fees and terminal commitments; and reconciliation workload and fragmented payment data.
- Segment payment journeys. High-value invoices, deposits and repeat payments may be suitable early candidates for open banking, while cards can remain available where they support customer preference or conversion. A blended payment strategy is often more commercially sensible than forcing every customer down one route.
- Measure implementation carefully. A single integration can unify more than 100 payment methods, while allowing you to test adoption, monitor conversion, track settlement speed and compare realised savings with the original business case. Since 2016, we have applied FTSE 250-level procurement leverage, payment expertise and technology delivery from our London and Essex base to help businesses make these decisions with clearer commercial evidence.
Review Payment Costs Before Budget Season
Card fees are often treated as a fixed cost of trading, but they are made up of scheme charges, processing margins and operational overhead that can be reviewed. Before budgets are finalised, compare every payment method against its effect on margin, cash flow, customer conversion and finance time.
The practical aim is not simply to pay less per transaction. It is to build a payment mix that protects EBITDA, gives customers a straightforward way to pay and lets your team see cleared funds and payment data without unnecessary delay.
Protect Margin With Lower Payment Costs
Digital Media Technology Solutions can assess where card acceptance costs are eroding margin and identify practical routes to lower transaction fees. We will benchmark the economics, settlement requirements and integration implications against your current payment mix. If you are reviewing payment costs ahead of a budget cycle or contract renewal, contact us for a focused commercial discussion.