The True Cost of Card-Scheme Fees Versus Open Banking
Card payments are convenient, but the real cost is rarely visible in one line on a supplier statement. Merchant service charges, interchange, scheme fees, terminal rental, fraud controls and settlement delays can all reduce margin. As Q4 transaction volumes rise, those costs can take a larger bite from EBITDA just when cash flow and operational capacity matter most.
We see this most clearly in businesses with high payment volumes, multiple locations or a mix of consumer, corporate and overseas customers. A modest percentage can look harmless until it is applied across millions of pounds of annual turnover. Since 2016, we have combined fintech knowledge with FTSE 250-level procurement leverage to help organisations in London and Essex review payment costs as part of a wider margin-improvement plan.
Protect Margin Before Q4 Card Costs Rise
Card acceptance is often treated as a fixed cost of trading. It should not be. Every payment method has a P&L effect, and that effect becomes more visible during peak periods such as Black Friday, Christmas trading and year-end invoicing.
A business processing significant card volume may be paying different rates depending on the card type, transaction channel and customer location. Premium cards, corporate cards, overseas cards and card-not-present payments can all cost more than the headline rate suggests. If those transactions make up a meaningful part of your payment mix, a blended percentage may hide where margin is being lost.
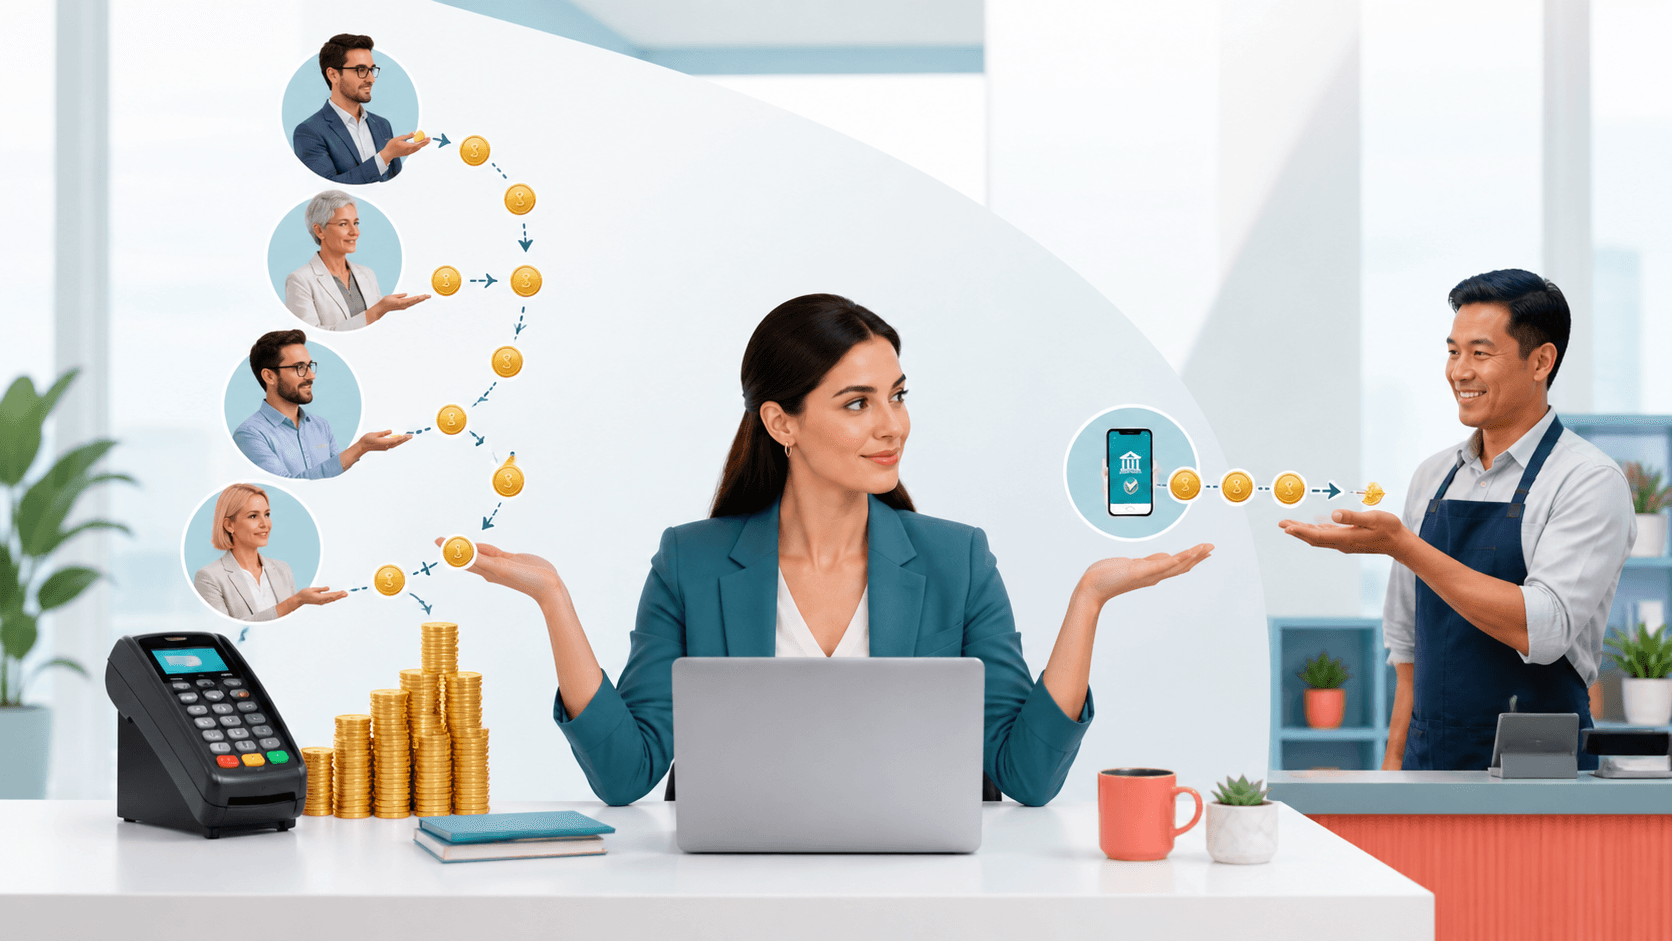
Open Banking changes the comparison. It is not simply another checkout button. It is an account-to-account payment route that can reduce reliance on card schemes, provide faster access to funds and create lower transaction fees for suitable payment journeys.
The objective is not to remove cards at all costs. Cards remain useful where customers expect payment flexibility or where a familiar checkout flow supports conversion. Our role is to identify where a different payment route can improve the economics without creating friction for your customers or finance team.
Expose the Full Cost of Every Card Payment
The advertised merchant rate is rarely the whole story. To understand what card acceptance is doing to profitability, we recommend separating every part of the payment cost stack.
Typical components can include:
- Interchange fees paid to the card issuer
- Card-scheme assessment and processing fees
- Acquirer margin, gateway charges and terminal rental
- PCI compliance, fraud tools and chargeback administration
- Currency conversion and higher charges for commercial or international cards
Costs also change according to the type of customer paying you. A business that accepts a large share of commercial, rewards or overseas cards may carry a different cost profile from one that mainly takes domestic consumer debit cards. Online transactions can add another layer, especially where payments pass through separate gateways, acquirers and reporting systems.
Consider a business processing £10 million annually at a blended card cost of 1.7%. That equates to £170,000 in annual processing charges before allowing for reconciliation time, chargeback handling and finance administration. Redirecting an appropriate share of that volume to a lower-cost route can improve EBITDA without selling one extra product or winning one extra customer.
This is where a detailed payment-cost review matters. Rather than accepting a single blended figure, we assess transaction types, supplier terms and operational workload to show where avoidable cost sits.
Know When Open Banking Creates Lower Transaction Fees
Open Banking payments allow a customer to approve a bank-to-bank transfer through their own banking app or online banking environment. Fewer intermediaries are involved than in a traditional card payment, which can support sub-1% transaction fees when the payment journey and supplier structure are right.
The strongest use cases are usually higher-value payments or situations where card fees are out of proportion to the transaction. We often assess Open Banking suitability for:
- Invoice payment links and B2B settlements
- Deposits and high-value online checkout payments
- Education fees and professional-services invoices
- Property-related payments
- Repeat customer payments where a simple bank-to-bank route is appropriate
A blanket switch is rarely the right answer. Customers should still have payment options that feel familiar and fit the way they buy from you. The better approach is to build a considered payment mix, presenting Open Banking where it makes commercial sense while retaining cards where speed, preference or payment flexibility matter.
That balance protects revenue as well as margin. It gives you the opportunity to reduce card-scheme exposure without forcing every customer into a payment method that does not suit the transaction.
Compare Fees, Cash Flow and Risk Before You Switch
Fees are only one part of the comparison. Card payments can be authorised immediately but may take days to settle, depending on acquirer terms and your contract. Faster access to cleared funds can improve working-capital visibility and reduce the gap between making a sale and receiving usable cash.
Risk also needs a clear-eyed assessment. Card payments operate within scheme-led chargeback processes, which can create administration, disputes and revenue leakage. Open Banking does not use the traditional card-scheme chargeback model. That does not remove the need for controls. You still need clear refund processes, authorised push payment fraud controls, customer support and accurate reconciliation.
Operationally, fragmented payment systems can create avoidable work across finance, customer service and operations. Separate reports, incomplete customer records and manual exception handling all consume time that should be focused on growth and performance.
A well-designed payment platform can bring more than 100 payment methods into one integration. That gives your team a clearer view of transaction costs, settlement performance, failed payments and exceptions. Payment automation and integrated systems can also reduce manual handling and improve the quality of data available for supplier negotiations.
Build a Payment Mix That Delivers Lower Transaction Fees
A useful review starts with twelve months of payment data, not assumptions. We recommend looking at gross card volume, blended rates, card type, customer geography, chargeback ratios, settlement terms, terminal estate and contract end dates. This separates genuinely necessary payment capability from avoidable supplier cost.
From there, payment journeys can be segmented. Invoice links, QR-code payments, deposits, high-value checkout and repeat transactions may be suitable places to introduce Open Banking as a preferred option. Customer messaging should explain security, speed and convenience in plain language, without making the process feel unfamiliar.
The financial model must be realistic. If £4 million of annual card volume moved from a 1.7% card cost to a 0.7% Open Banking cost, the indicative annual processing-cost reduction would be £40,000. The final case should also account for implementation work, supplier terms, customer conversion rates and internal administration savings.
- Export twelve months of transaction-level data from your acquirer, gateway and payment platform, then separate volume by card type, channel, customer geography and settlement period.
- Calculate the fully loaded cost for each payment route, including interchange, scheme fees, acquirer margin, gateway charges, terminal costs, chargeback administration and reconciliation time.
- Identify payment journeys where Open Banking is commercially suitable, starting with invoice payments, deposits, high-value transactions and repeat payments where lower fees can outweigh any change in customer behaviour.
- Run a controlled implementation with clear customer messaging, finance reconciliation processes, refund procedures and fraud controls before extending the new payment route across additional transactions.
- Measure conversion, settlement timing, transaction fees, chargeback ratios and administration time each month, then retain cards and Open Banking only where each route delivers the strongest outcome for margin, cash flow and customer convenience.
Turn Your Payments Review Into a Q4 Margin Gain
September is a sensible point to review payment costs before Q4 volumes, year-end budgets and supplier renewals increase the pressure. The most useful assessment looks beyond headline rates to settlement timing, operational friction, transaction mix and the role each payment method plays in the customer experience.
A clear payment strategy does not mean choosing cards or Open Banking. It means assigning each transaction to the route that best supports margin, cash flow and customer convenience. That gives finance and operations leaders a stronger basis for decisions before peak trading exposes the full cost of an outdated payment setup.
Protect Margin With Lower Payment Costs
Digital Media Technology Solutions helps finance and operations leaders identify where card acceptance is eroding EBITDA and where Open Banking can reduce avoidable cost. See how to achieve lower transaction fees, faster settlement and fewer chargeback exposures through a payment setup built around your trading model. For a practical review of your current fee structure and integration options, contact us.