Direct Debit admin can quietly weaken cash-flow control. We often see UK businesses managing collections, supplier payments, mandate changes and failed payments through spreadsheets, bank portals and disconnected finance systems. The result is slow reconciliation, poor visibility and senior finance staff spending too much time resolving exceptions.
For businesses turning over £1m to £250m, this is not simply an admin issue. A small rise in overdue collections, duplicate payments or unreconciled transactions can put working capital and EBITDA under pressure. Founded in 2016, from our London and Essex base, we have combined FTSE 250-level procurement leverage with payment, systems and operational experience to help businesses tighten these controls.
Stop Direct Debit Admin From Draining Working Capital
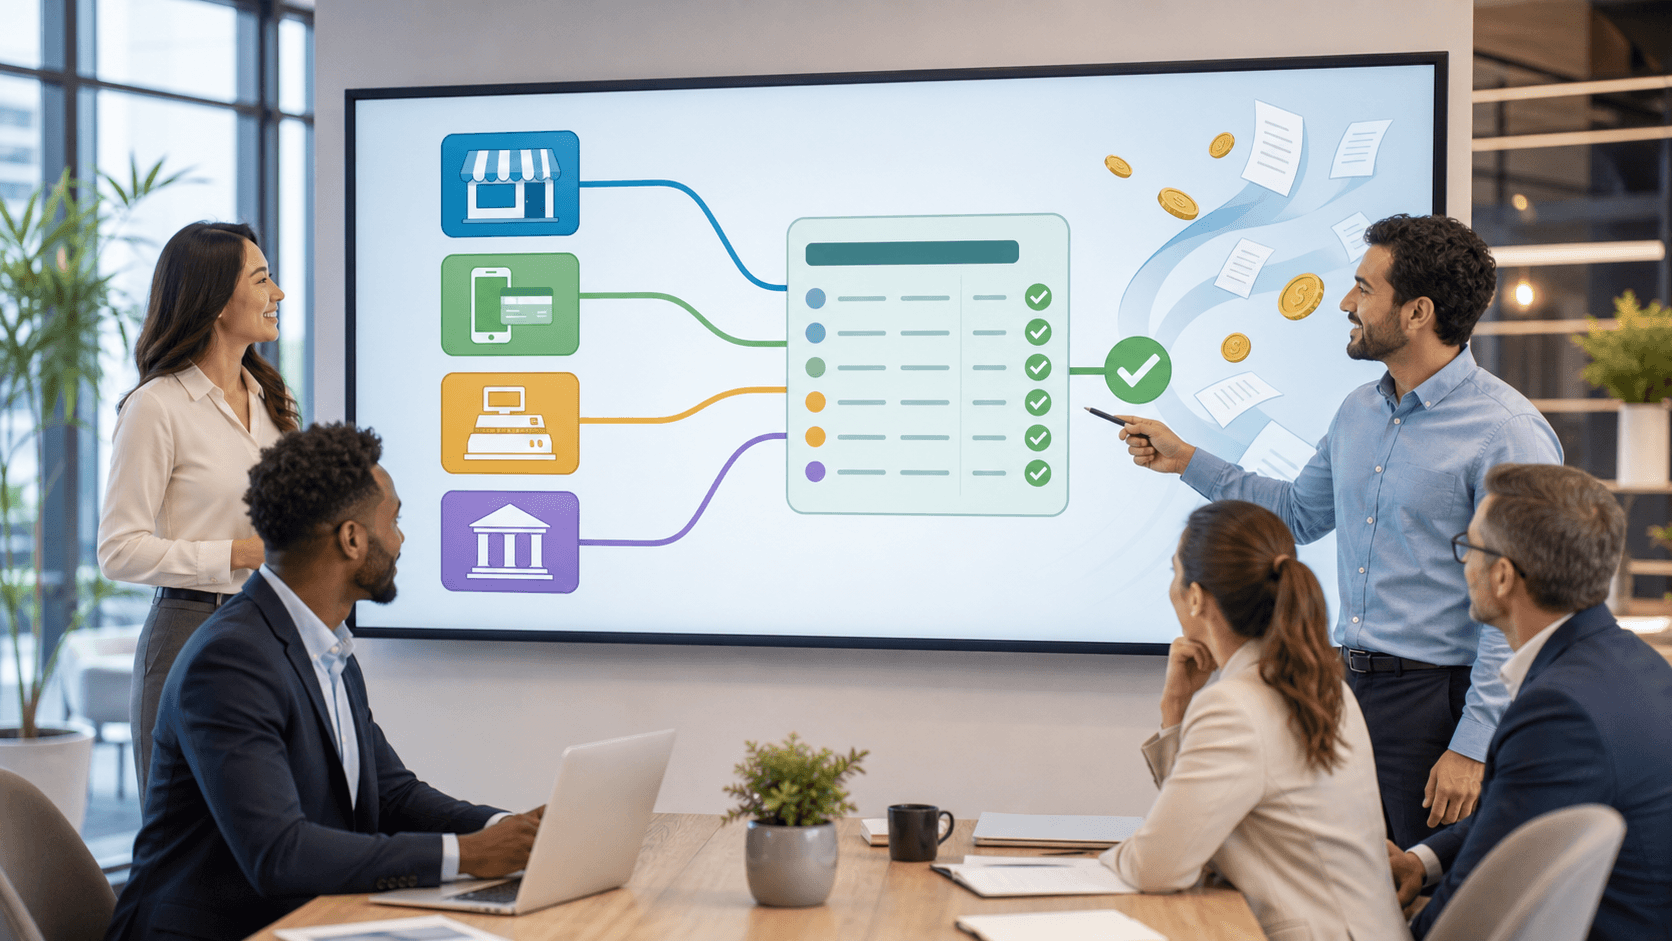
Direct Debit automation creates a controlled payment workflow, not just a faster way to submit files. When payment data moves between your CRM, accounting platform, bank and reporting tools without manual rekeying, your team can act on clearer information.
Manual processes often hide the true cost of payment administration. A finance team may spend hours checking files, matching receipts, updating customer records and chasing failed collections. Meanwhile, overdue balances rise and cash forecasts become less reliable.
The aim is straightforward: give your leadership team a timely view of what is due in, what is leaving the bank and what needs attention.
Know When Direct Debit Processes Need Automation
October is a sensible point to review payment controls. Year-end close, January cash requirements, annual budgets and seasonal trading peaks all depend on reliable forecasts. If you expect Christmas demand, January renewals or major Q1 supplier commitments, you need confidence in your incoming and outgoing cash.
We recommend reviewing automation when you see any of these signs:
- Payment volumes are rising faster than the finance team's capacity.
- Multiple legal entities or sites are using separate processes.
- Failed collections and mandate changes require regular manual follow-up.
- Reconciliation waits until month-end spreadsheet checks.
- You are changing ERP, CRM, accounting, banking or payment systems.
In a growing service-led or multi-site business, a larger Direct Debit book can quickly create delayed collections and unclear debtor reporting. Cash application slows, aged debt grows and senior staff are pulled into exception chasing. A system change is the right time to remove those workarounds, rather than carrying them into a new platform.
Why Automate Your Direct Debits Before Year End
The commercial case rests on cash, labour and error reduction. If you automate your direct debits, you can apply consistent collection dates, route exceptions quickly and maintain a clear record of mandates, collections, refunds and failed payments.
Start with the P&L. Manual payment handling adds finance overhead. Weak visibility may also lead to unnecessary short-term borrowing, missed supplier discounts or late cost-control decisions. We assess the opportunity by looking at three areas:
- Cash released by reducing overdue customer balances.
- Finance time spent processing, correcting and reconciling transactions.
- Margin protected by preventing payment errors, duplicate charges and missed collections.
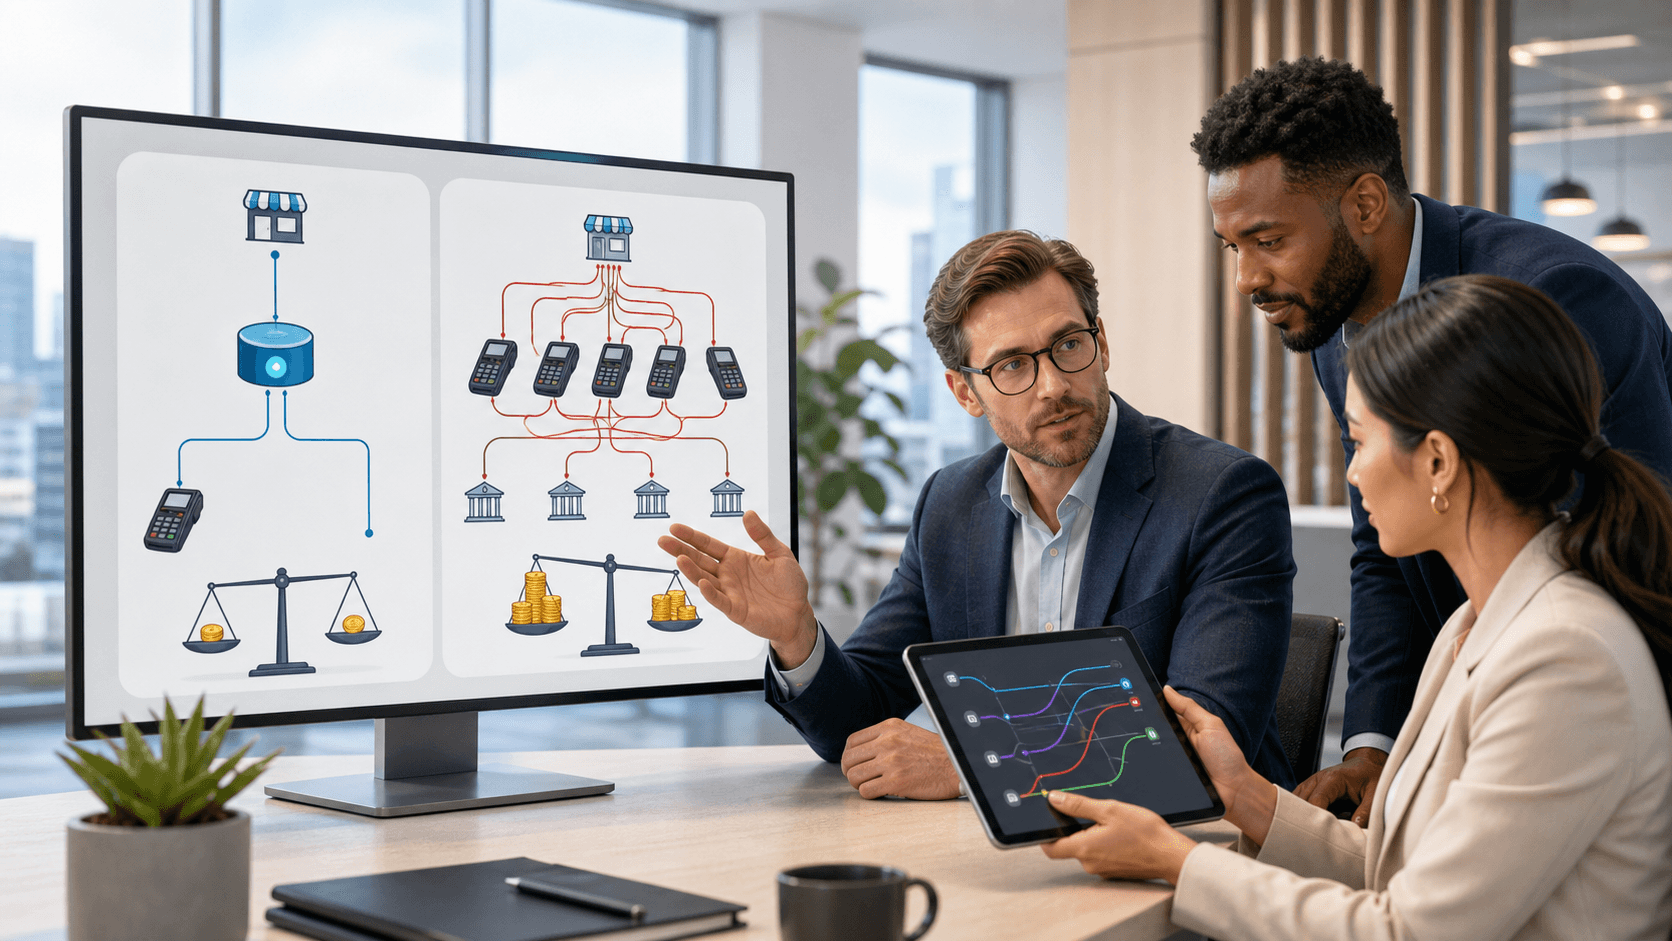
Direct Debit is not always the best collection route. For immediate settlement, selected one-off payments or lower card-scheme costs, Open Banking pay by bank may be a better fit. Depending on the payment mix, sub-1% transaction fees may be available. The right answer is a payment strategy that matches each collection type to the appropriate rail, rather than forcing every transaction through one method.
Where you collect recurring revenue by Direct Debit, your workflow must still meet Bacs requirements, retain accurate mandate records and deal with indemnity claims properly. Automation should strengthen those controls, not hide them.
Build a Controlled Direct Debit Payment Workflow
A controlled implementation begins with process mapping. We work from customer or supplier onboarding through mandate capture, payment scheduling, bank submission, reconciliation, failed-payment handling and reporting. This exposes where people rekey data, override approvals or work outside approved systems.
A practical workflow should include:
- Named ownership across finance, operations and customer service.
- Approval limits and segregation of duties for payment changes.
- Secure mandate storage, audit trails and visible exception queues.
- Written procedures for cancellations, refunds, disputes and failed payments.
- A supplier Direct Debit review against contracts, usage and agreed unit rates.
Success should be measured in commercial terms, not by whether staff log into a new platform. Track collection success rate, failed-payment rate, days sales outstanding, reconciliation time, manual touches per transaction, disputed collections and forecast accuracy.
In one anonymised multi-site service business, finance staff were using manual uploads and spreadsheet reconciliation across customer collections and recurring supplier payments. Integrating payment status with its finance system created a visible exception queue, reduced repetitive matching and gave management faster debtor and cash-position reporting. The commercial outcome was tighter control of overdue collections and supplier payments, while finance capacity moved towards debtor analysis, supplier control and commercial planning. That is where automation begins to support EBITDA rather than simply changing the format of admin.
Connect Banking, Finance Systems and Supplier Data
Automation fails when it becomes one more disconnected platform. Payment status should update customer records, accounting data and reporting tools without requiring someone to copy information between systems.
Open Banking can add another layer of visibility. Real-time bank data and account information can help your finance team monitor cash positions, spot incoming and outgoing patterns, and make earlier decisions about funding, supplier payments and collections activity.
Supplier Direct Debits deserve equal attention. Recurring charges can continue long after a contract end date, tariff change, service reduction or price rise. We recommend pairing automated reporting with a supplier review covering energy, telecoms, insurance, payment terminals, shipping, software and other recurring operating costs.
Technology should support commercial control. Our procurement work can secure savings of up to 60% in suitable categories, subject to your spend profile, supplier market and contract position. There is little value in automating a payment that should have been challenged, renegotiated or cancelled.
Review Your Direct Debit Controls Before Q4 Closes
Before Q4 closes, review how mandates and payment changes are approved, how quickly payments are reconciled and whether every recurring supplier payment remains commercially justified. Those three checks will reveal whether your current process protects cash or simply processes transactions.
Direct Debit automation should give you a clearer cash position, less repetitive finance work and stronger control over recurring payments. Treat it as part of a wider review of payment rails, fee structures, supplier costs, integrations and operational workflow, with each measure tied back to cash flow, operating cost and EBITDA.
Turn Payment Data Into Better Margin Decisions
Digital Media Technology Solutions can assess where Direct Debit collection, payment acceptance and reconciliation are creating avoidable cost or delay. See how we can automate your direct debits alongside Open Banking payment routes to improve settlement speed and reduce processing fees. If you need a practical review of the commercial and operational case, contact us to arrange a focused discussion with our team.