Stop Paying for Payment Complexity You Cannot See
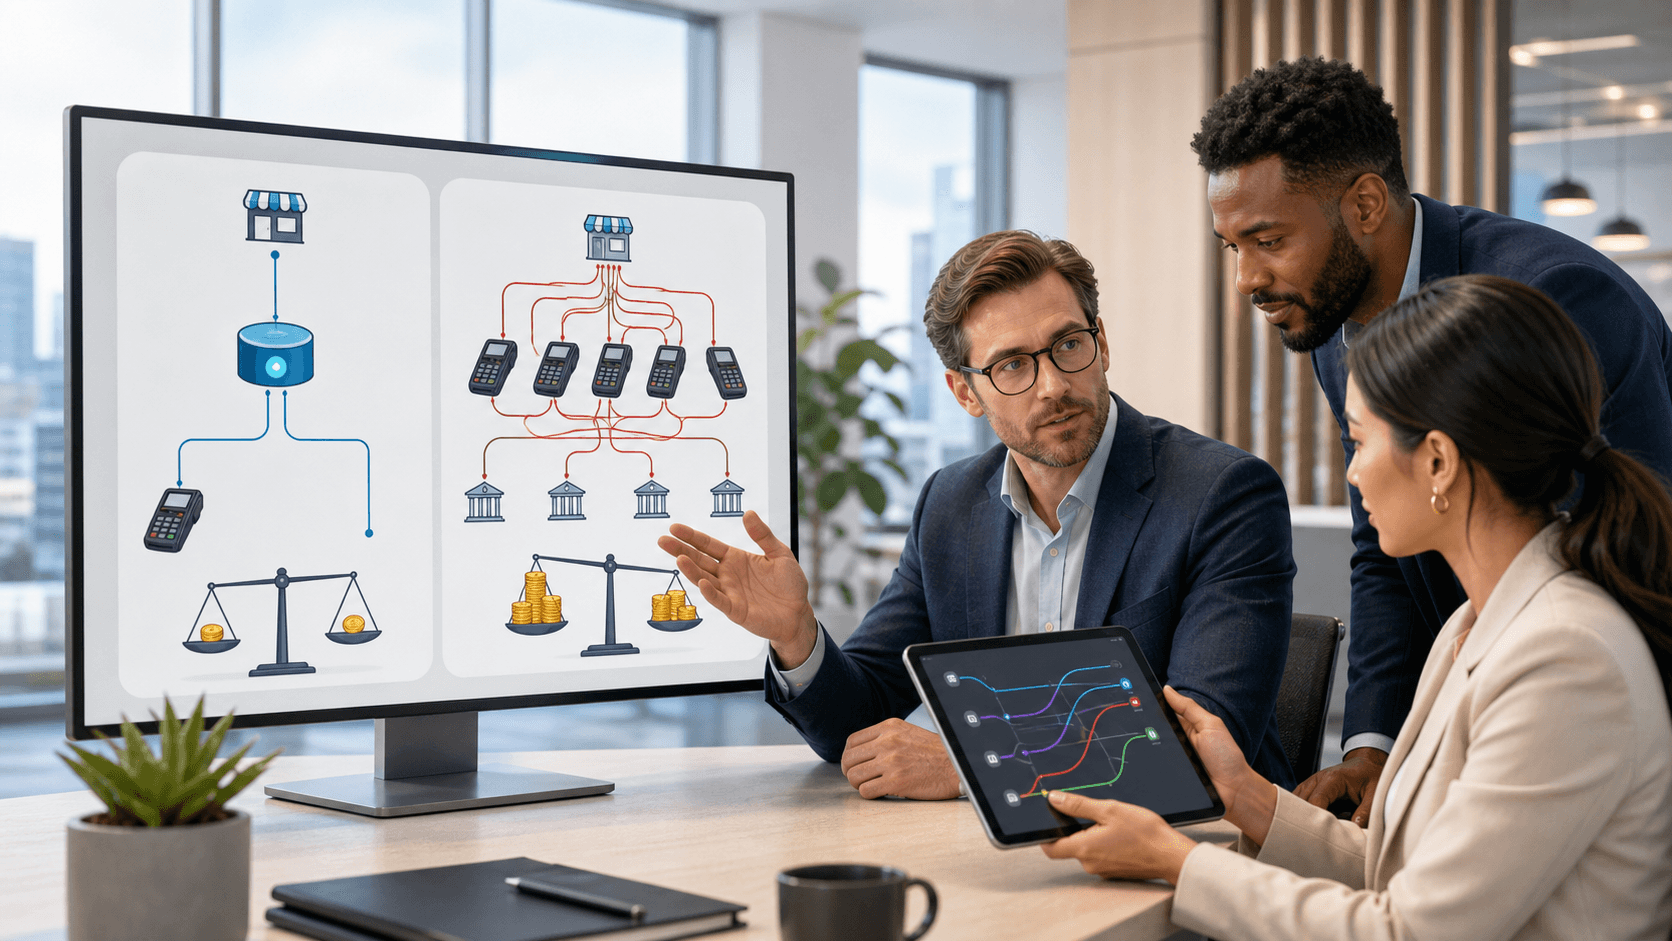
Choosing payments infrastructure is straightforward in principle. You can connect separate gateways for cards, wallets, bank payments and international methods, or choose one integrated payments solution that brings those methods into a single operating environment. The transaction rate on a supplier proposal is only one part of the decision. The bigger impact often sits in reconciliation time, engineering maintenance, settlement visibility, supplier management and accounting errors.
For business owners, CFOs and Operations Directors under margin pressure, an unmanaged multi-supplier payment estate can quietly increase overhead. Multiple gateways can be justified for resilience or access to a particular market, but they should be a controlled exception, not the result of supplier creep. Since 2016, we have worked as a London and Essex-based advisory and technology partner, helping organisations simplify supplier estates, control operating costs and improve profitability.
What an Integrated Payments Solution Changes
A single integration gives finance and operations teams one place to review transactions, settlements, refunds, chargebacks, webhooks and reconciliation data. Instead of downloading exports from several portals, your team works from one reporting structure and one consistent set of transaction references.
That matters at month end. Finance needs to match gross sales, processing fees, net settlement and refunds without spending hours translating different provider formats. Separate gateways often use different payout cycles, fee descriptions, reserve arrangements and reference numbers. None of these differences are impossible to manage, but each one adds time and creates more room for mis-postings.
With an integrated payments solution, we would expect your reporting process to be clearer across:
- Gross transaction values and payment method data
- Fees deducted before or after settlement
- Refunds and chargeback activity
- Settlement dates and expected cash receipt
- Exceptions requiring finance or customer service action
Operations also benefits. One integration generally means fewer webhook configurations, fewer API dependencies and fewer technical points for internal teams to monitor. Engineering teams can spend less time maintaining separate payment connections, while finance and customer service teams face less manual administration. This is not just tidier technology. It is a practical way to reduce recurring operational work.
When to Review Payment Operations
October is a sensible point to review payment operations before peak trading, year-end close and the next budgeting cycle. Businesses carrying unclear settlement data, fragmented reporting and unmanaged supplier costs into a new financial year risk preserving overhead that could have been removed. Payment infrastructure deserves board attention because it affects cash flow, financial controls, operational workload and profitability.
Why Multiple Gateways Multiply Hidden Profit Costs
A gateway comparison can look favourable when it focuses on a headline processing rate. The true commercial picture is wider. Separate providers may each bring gateway charges, acquiring fees, minimum commitments, foreign exchange margins, refund handling rules, chargeback administration and supplier management time.
The lower rate is not always the lower total cost. If your finance team has to reconcile multiple settlements every week, or your technology team has to maintain several integrations, internal overhead can outweigh a modest saving on a single payment type. Those hours are a recurring operating expense, and they reduce EBITDA just as surely as any supplier invoice.
Fragmented settlement data creates a further control issue for the CFO. One provider may settle quickly, another may deduct fees at source, while another may hold funds under a reserve arrangement. Cash forecasting becomes less certain when incoming payments arrive on different days and are reported in different ways.
We often see this pattern in multi-site and online businesses that have added payment providers over time. A new sales channel needs a wallet option, an overseas market needs another method, or a department signs up to a specialist provider. Before long, finance is working across several portals and exports, while technology maintains separate integrations. The problem is not inconvenience. It is unmanaged operating expenditure.
Why Total Cost Matters More Than Processing Rates
Before choosing between consolidation and multiple suppliers, we recommend a total cost of ownership review. Start with annual figures, not a single percentage rate or one month of trading. This gives you a clearer view of the P&L effect across ordinary trading periods, peak demand and refund-heavy periods.
Your assessment should include:
- Transaction, interchange and assessment fees where applicable
- Gateway charges, refund fees and chargeback ratios
- Foreign exchange charges and international settlement terms
- Settlement timing, reserve arrangements and cash flow impact
- Engineering support, reconciliation hours and supplier management time
A single supplier structure can make budget setting and variance analysis easier. Fee reporting is more consistent, settlement data is easier to trace and finance has a cleaner view of what changed when volumes rise. Predictability matters when you are protecting margin and planning working capital.
Consolidation does have a trade-off. Splitting volume between providers can create more negotiation leverage, while one provider may create lock-in if contracts, data access and integration design are poorly managed. We do not recommend accepting the first consolidated offer. Procurement discipline still matters. You need transparent terms, clear fee definitions, reporting access, service commitments and realistic exit options before moving to one integrated payments solution.
How to Keep Supplier Leverage Without Losing Operational Control
Simplicity does not have to mean dependency. The strongest approach is often one primary operating integration, supported by commercial protections and a defined resilience plan. This keeps day-to-day payment operations under control without leaving your business exposed to unclear supplier terms.
As an independent commercial and technology partner, we assess the current provider estate, benchmark supplier terms and identify where consolidation, renegotiation or a different payment architecture could improve margin. Our FTSE 250-level procurement leverage can uncover cost reduction opportunities of up to 60% across relevant procurement categories, although every payment review must be assessed on its own facts.
A practical review should proceed in four steps:
- List every gateway, processor, acquirer and payment method currently in use.
- Calculate the annual supplier and internal operating burden, including reconciliation and engineering time.
- Review contract length and renewal provisions, pricing review clauses and volume assumptions, service level agreements and incident reporting, data ownership and access to transaction records, and settlement terms, termination support and migration rights.
- Test whether one integrated payments solution could provide the payment methods, reporting and resilience you require without creating unacceptable supplier risk.
A contingency route may be sensible for critical payments or high-risk trading periods. What should be avoided is allowing each department to add a new gateway without finance, operations and technology approval. That is how supplier creep begins. The right decision is the one that gives your teams clear data, controlled operations and a payment estate that supports margin rather than quietly eroding it.
Turn Payment Complexity Into Margin Control
Digital Media Technology Solutions can assess whether an integrated payments solution would reduce processing costs, reconciliation time and supplier exposure across your estate. We examine fee structures, settlement flows and operational dependencies to identify the commercial case before change is made. If you need a clear payment strategy built around margin and control, contact us to arrange a discussion.