Stop Chargebacks From Eroding Your Hard-Won Margin
Chargebacks are not simply a customer service issue. Every dispute can mean lost revenue, unrecovered fulfilment costs, administration time, scheme fees and greater payment acceptance risk. As card volumes grow, these losses can quietly erode profit margins, even when you delivered the product or service correctly.
For business owners, CFOs and operations directors, the board-level concern is repeatable payment leakage. The most reliable way to remove card scheme chargebacks is to reduce reliance on card rails where open banking payments are commercially suitable, while tightening controls around the card payments you still accept.
Founded in 2016, we are a London and Essex-based advisory and technology partner with FTSE 250-level procurement leverage. Our payment processing work brings together sub-1% transaction fees, fast settlement and a single integration supporting more than 100 payment methods.
Quantify the Full Cost of Every Payment Dispute
A chargeback starts with the original sale, but its P&L effect goes much further. You may lose the revenue, cost of goods, delivery or service time, fulfilment spend, chargeback fee and the time your finance or operations team spends building a defence. Future customer value may also disappear.
This becomes a material EBITDA issue in subscription businesses, hospitality, professional services and e-commerce. A high dispute ratio can also raise concerns with acquirers and card schemes, which monitor dispute performance. Persistent problems may lead to extra monitoring, reserve requirements, higher processing costs or fewer acquiring options.
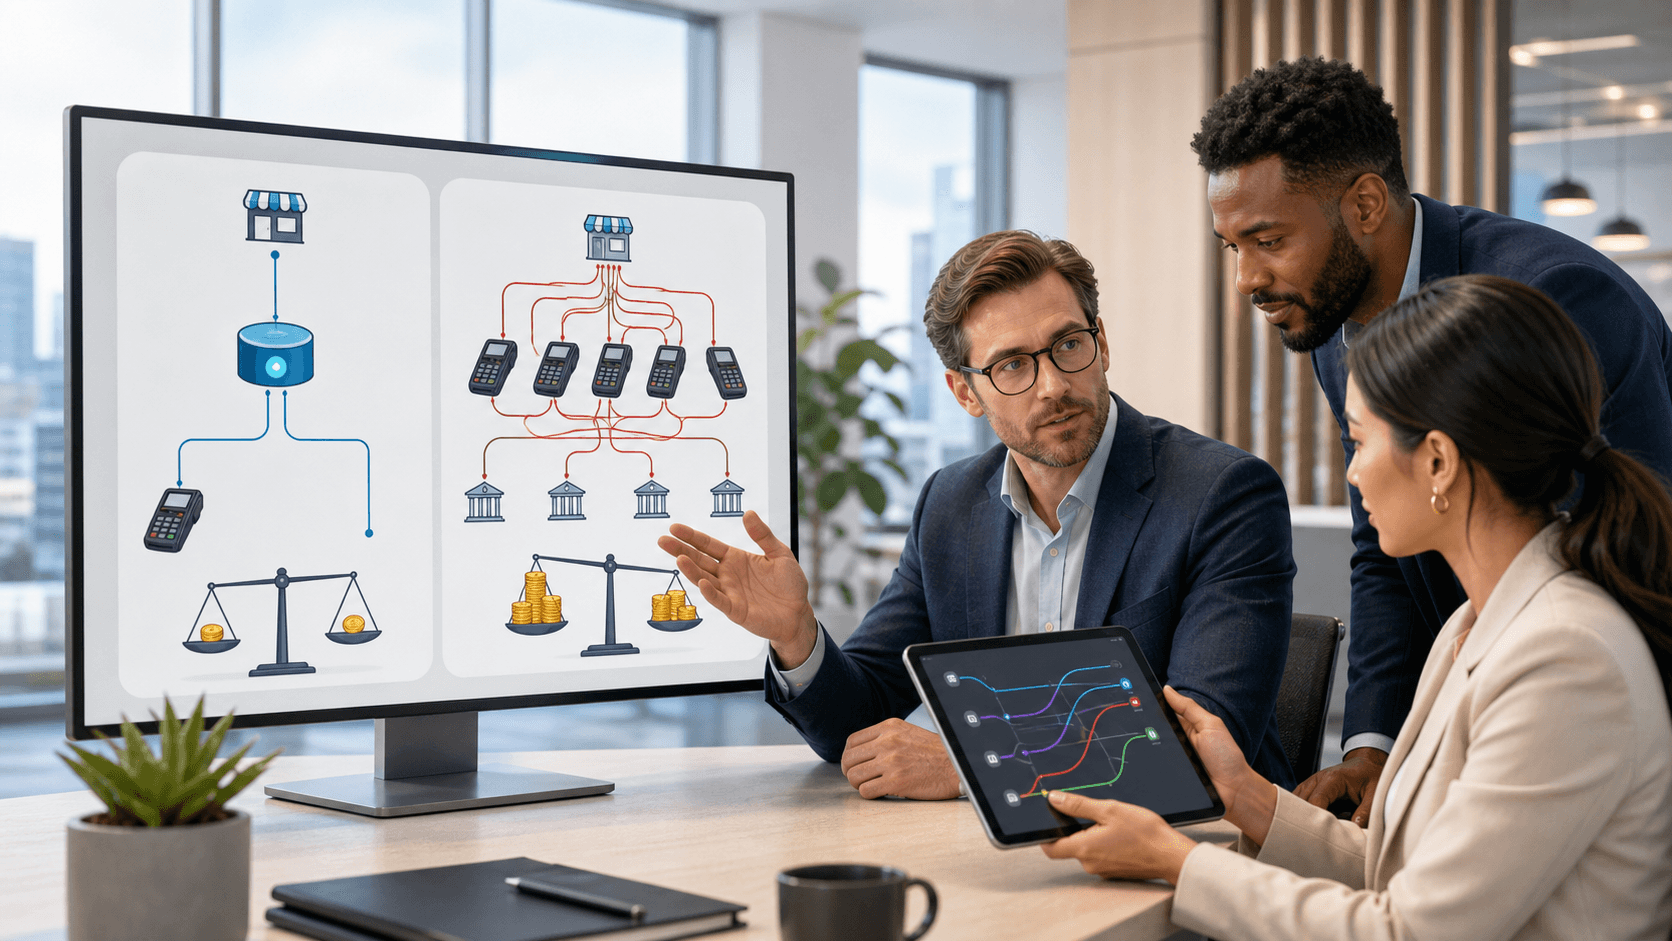
In an anonymised review for an e-commerce retailer following peak trading, the finance team was defending disputes order by order while order, delivery and customer-contact records sat in separate systems. Mapping reason codes to fulfilment data showed which transactions needed clearer descriptors and proof of delivery, and which higher-value orders were better suited to account-to-account payment.
A useful review should calculate:
- The disputed value and lost gross margin
- Fulfilment, shipping or service delivery costs
- Chargeback fees and staff hours per case
- Win rates by reason code, channel and payment method
- The chargeback ratio and its impact on acquiring risk
The disputed order is rarely the real issue. The payment model, customer communication and fragmented data behind it are what create repeatable leakage.
Review Exposure Before Peak Trading and Budget Decisions
October is a sensible time to assess payment risk. Black Friday, Christmas trading, year-end reporting and next-year budgets can all put pressure on payment operations. Weaknesses that seem manageable at lower volumes can become expensive when transaction numbers increase quickly.
Warning signs include unclear billing descriptors, delivery delays, rising friendly fraud, slow access to funds, increasing payment fees and an operations team spending too much time assembling evidence. If customers cannot recognise a transaction or resolve a complaint promptly, they may go straight to their card issuer.
We recommend reviewing chargeback exposure alongside merchant acquiring contracts, gateway costs, payment terminal fees and cash conversion. A supplier renewal or budget cycle is the right moment to benchmark the entire payment stack, rather than accepting legacy rates and disconnected providers.
Finance teams should maintain a monthly chargeback dashboard covering:
- Dispute volume and disputed value
- Chargeback ratio by payment method and sales channel
- Reason codes, win rate and fee costs
- Staff time spent responding to disputes
- Customer segments, products and fulfilment patterns
That visibility gives finance and operations leaders a shared view of where margin is being lost.
Move Suitable Sales to Open Banking Payments
Open banking provides a practical alternative for suitable transactions. Instead of entering card details, the customer approves a secure account-to-account payment through their bank. Funds can settle quickly, and the payment does not run through the card scheme chargeback process.
That distinction matters. Account-to-account payments can deliver zero card scheme chargebacks because no card transaction is involved. Payment risk does not disappear, however. You still need effective fraud prevention, customer authentication, clear refund policies, fulfilment records and attention to relevant consumer protection and authorised push payment obligations.
We see the strongest commercial fit in areas such as high-value invoices, deposits, recurring B2B payments, professional services, education fees, vehicle sales, membership payments, hospitality balances and e-commerce baskets where card fees and disputes take a disproportionate bite from margin.
Moving appropriate payments away from card rails can remove interchange-related card costs, reduce chargeback administration and improve cash flow through faster settlement. Our role is to assess the payment mix, transaction volumes and integration requirements, then identify where open banking and alternative methods make commercial sense.
Control the Card Payments You Still Need
Eliminating chargebacks does not mean removing cards entirely. Cards remain important where they support customer choice and conversion. The objective is to use them where they add value, while reducing avoidable disputes through better commercial and operational control.
Clear trading names, recognisable payment descriptors, accurate delivery dates, transparent cancellation terms and simple refund routes all matter. Many disputes begin because a customer does not recognise the transaction or cannot get a quick answer when something goes wrong.
The technical side matters too. We recommend strong customer authentication where appropriate, evidence captured at the point of sale, proof of delivery or service completion, consistent CRM and order records, and alerts for higher-risk transactions. When booking, ERP, e-commerce and CRM systems do not share data, dispute responses become slower and weaker.
A single payment integration can bring cards, bank payments and alternative methods into a more manageable process. This supports cleaner reconciliation, leaner finance operations and clearer reporting on payment costs by channel. Where systems are fragmented, we focus on the operational cause rather than repeatedly paying to defend the outcome.
Build a Payment Strategy That Protects EBITDA
- Identify the products, channels and payment types creating disputes by reviewing chargeback ratios, reason codes, order values and fulfilment patterns over at least 12 months.
- Calculate the full cost per dispute, including lost gross margin, fulfilment spend, chargeback fees, staff time, reserve requirements and the impact on acquiring terms.
- Move suitable transactions to open banking and lower-cost routes, starting with high-value invoices, deposits, recurring B2B payments and transactions with disproportionate card fees or dispute exposure.
- Redesign controls for the card transactions that remain by improving descriptors, refund routes, customer authentication, proof of delivery and the quality of evidence held across payment, CRM and order systems.
Payment choice affects transaction costs, settlement speed, working capital, customer experience, fraud exposure and operational workload. It belongs in the CFO's EBITDA improvement plan and the operations director's efficiency programme, not in an isolated payments project.
Before Q4 volume peaks or annual budgets are finalised, the strongest position is a clear view of dispute data, payment method mix and supplier terms. Reducing unnecessary card dependency can protect margin, lower finance administration and improve access to cash without weakening the customer experience.
Replace Chargeback Risk With Faster Cash Flow
Digital Media Technology Solutions can assess where card fees, disputes and settlement delays are eroding EBITDA, then map a practical route to lower-cost payment acceptance. See how open banking can support instant settlement, sub-1% transaction fees and zero chargebacks for suitable transactions. To review your payment mix and implementation options, contact us for a focused commercial discussion.