A sale is not the same as usable cash. Your customer may complete a payment in seconds, yet card takings can remain unavailable for days. That gap can put pressure on payroll, supplier payments and stock decisions, even when sales look healthy.
We help businesses treat payment timing as a cash flow issue, not just a finance admin task. Instant settlement through Open Banking can shorten the time between accepting money and having cleared funds available to use.
Stop Letting Payment Delays Dictate Your Cash Position
Card payments are often authorised immediately, but authorisation is not settlement. The customer's bank has approved the payment, yet the funds may still move through card schemes, acquirers and scheduled settlement cycles before reaching your account. Weekends, bank holidays and high-volume trading periods can add further delay.
For a growing business, this creates uncertainty. You may see sales in your reporting, but your finance team cannot rely on those funds until they have cleared and become available.
Open Banking account-to-account payments offer a different route. Funds can move directly from the customer's bank account to the business account, giving you earlier confirmation and, where the payment set-up and participating banks allow, faster access to cleared funds.
Since founding Digital Media Technology Solutions in 2016, we have worked as a London and Essex-based business advisory and technology partner. Our focus is simple: improve profitability by reducing avoidable payment costs and making payment operations easier to control. Our FTSE 250-level procurement leverage also strengthens our ability to benchmark supplier costs, challenge payment pricing and improve commercial terms.
See When Delayed Settlement Starts Eroding Margin
Settlement delays become a P&L concern when you have to fund the gap between making a sale and receiving the money. This often becomes more visible in October, when Q4 trading, year-end stock purchases and budget planning place extra pressure on working capital.
We recommend reviewing your payment position when you see recurring signals such as:
- Regular use of an overdraft to cover routine cash gaps
- Supplier payments being delayed despite strong sales activity
- Disputes or confusion around merchant settlement reports
- Rising processing fees as transaction values increase
- Manual daily reconciliation taking up finance team time
A settlement delay has a cost beyond the merchant fee shown on a statement. If you rely on overdraft facilities, invoice finance or short-term borrowing while waiting for money already earned, your true cost of accepting payments rises. There is also the time spent checking reports, matching receipts and chasing exceptions.
Timing matters particularly for ecommerce businesses, hospitality operators, professional services firms, wholesalers, multi-site businesses and any organisation with significant supplier or payroll commitments. We often see this pattern with businesses processing high-value customer payments each week: revenue is growing, but card settlement takes several working days. Moving suitable payment journeys to Open Banking can give finance teams earlier visibility and reduce the need to bridge short-term cash gaps.
For example, an anonymised professional services client processing high-value invoices had card settlements arriving over several working days, while its finance team manually matched payment notifications against its accounting records. After introducing Open Banking for suitable invoice payments, the business reduced reconciliation time by 12 hours per month and had payment confirmation available on the day customers paid, improving its daily cash visibility.
Understand How Instant Settlement Improves Working Capital
Working capital is not simply the revenue shown in management accounts. It is the cash you can use to run the business today. Faster settlement can shorten your cash conversion cycle, helping you pay suppliers on time, replenish stock, take early-payment discounts where available and reduce unnecessary borrowing.
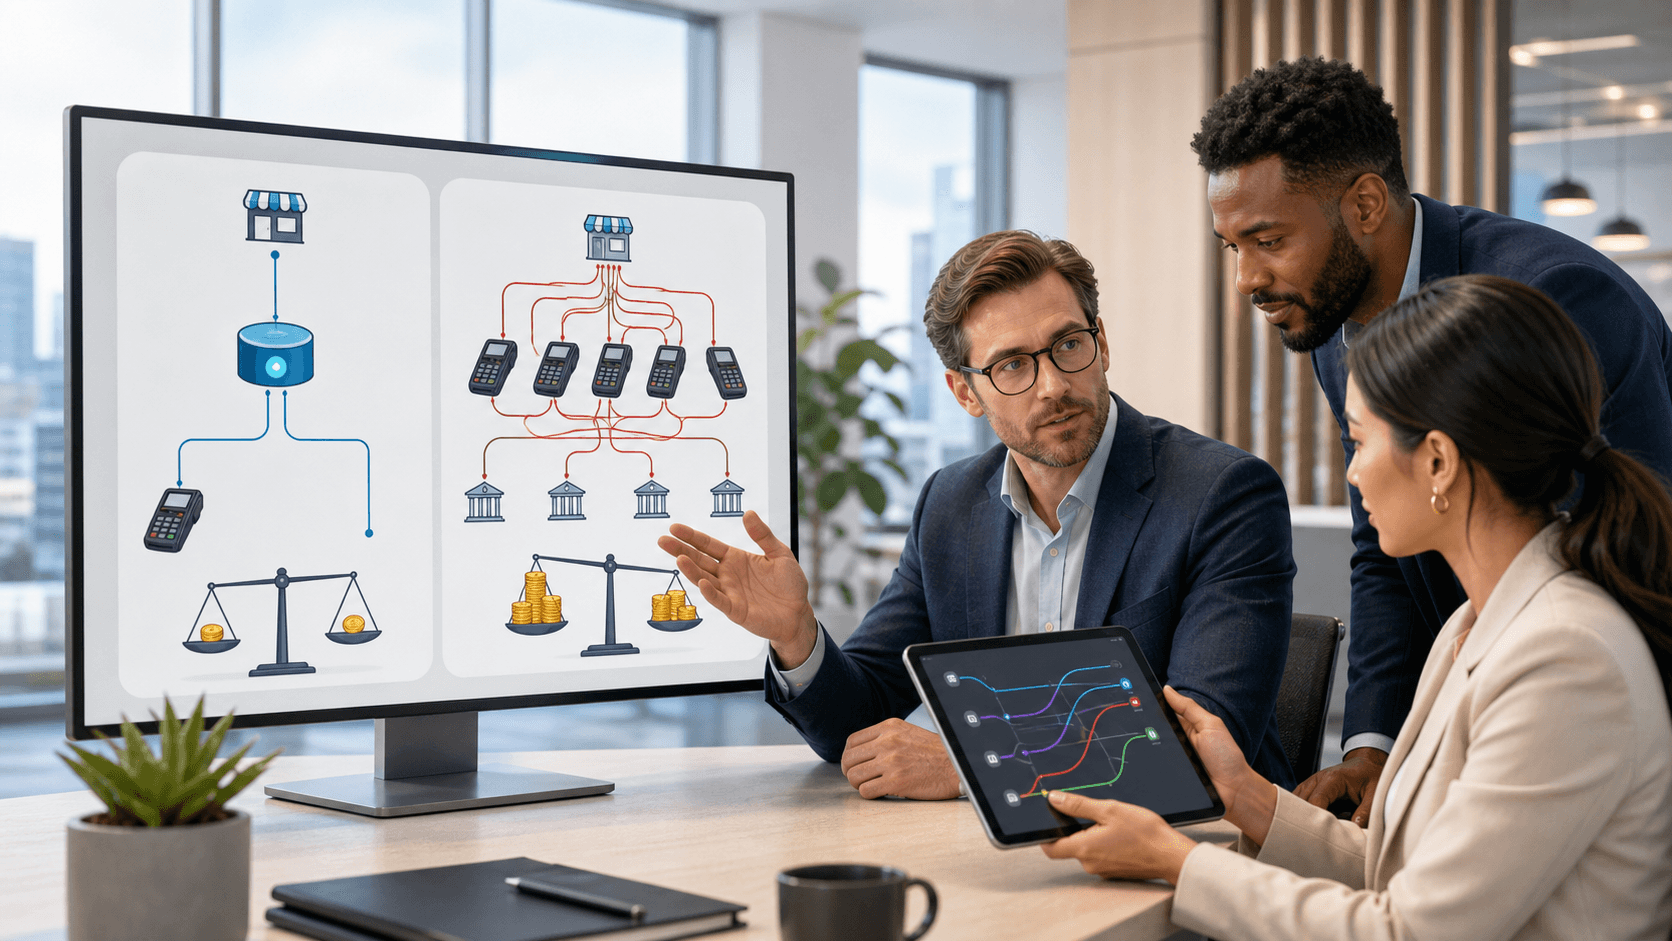
Traditional card flows can involve card-scheme processes, acquirer settlement cycles and interchange-related costs. With an account-to-account payment, the customer pays directly from their bank account. This can simplify the payment route and give you greater control over how and when funds arrive.
The commercial case is clear. Open Banking payment solutions can offer transaction fees below 1%, depending on volumes and requirements. Percentage-based card costs rise as sales values rise, which means high-value payments can carry a disproportionate margin impact.
For a CFO or Finance Director, the combined effect matters:
- Faster access to available funds can improve cash forecasting
- Lower payment fees can protect EBITDA without additional sales volume
- Reduced reconciliation work can lower payment-related operating costs
- Better visibility can support more confident supplier and payroll planning
Settlement outcomes are not identical in every situation. They depend on participating banks, payment set-up and the controls around each payment flow. The aim is not to replace every existing method overnight. It is to build a payment mix that gives you more control over cash, cost and operational effort.
Receive Funds Faster Without Adding Finance Costs
External finance can solve a cash shortage, but it does not remove the underlying delay. If you are borrowing against money that customers have already paid, the first question should be whether the payment process itself is creating avoidable pressure.
Open Banking can help you receive funds faster while reducing exposure to the card-scheme chargeback model. Account-to-account payments do not operate through the same chargeback process as card payments. That can reduce operational disruption and uncertainty around funds already received, although clear refund processes and payment controls still matter.
To understand the full cost of payment acceptance, we advise finance leaders to assess more than headline merchant fees. Review:
- Monthly card volume and average transaction value
- Average card settlement delay
- Overdraft, invoice finance or short-term borrowing use
- Chargeback administration time and refund processes
- Manual reconciliation workload across systems
The right starting point is usually high-value, repeat, invoice-based or B2B payments. Deposits, trade accounts and online payments are also strong candidates where customers value a direct bank payment option. This approach allows you to improve payment mechanics without removing card choice where it still makes commercial sense.
Build a Controlled Open Banking Payment Operation
Instant settlement works best when it sits inside a controlled payment operation, not as an isolated technology purchase. We recommend a structured implementation that connects payment data, finance processes and governance.
- Map current payment flows. Review card terminals, ecommerce checkout, invoices, settlement times, transaction fees, refunds and reconciliation workloads.
- Identify priority use cases. Start where faster settlement and lower fees will have the strongest impact, such as high-value invoices, deposits, trade accounts and online payments.
- Connect payment data with finance operations. Payment confirmation, settlement status and customer records should feed into your accounting, CRM or ERP environment to reduce reporting gaps.
- Set clear controls. Define who can issue payment requests, approve refunds, access reports and monitor exceptions. This supports finance governance and fraud prevention.
- Measure outcomes monthly. Track settlement speed, payment completion rates, processing fees, reconciliation time, forecasting accuracy and borrowing requirements.
A business with fragmented payment systems can centralise account-to-account payment options through a single integration. The result is a clearer daily cash position, less manual matching and more reliable information for finance and operations teams.
Make Q4 Cash More Predictable Before Year-End
Autumn is a sensible time to review settlement timetables before peak demand, supplier commitments and year-end payroll cycles add further strain. Delayed settlement, card fees and disconnected systems can create pressure that does not show clearly in top-line sales figures.
A practical review should focus on when money becomes available, what it costs to accept, how much manual work it creates and whether short-term borrowing is covering a payment delay. Faster access to cleared funds can support supplier confidence, improve payment visibility and protect operating margin when cash matters most.
Reduce Payment Costs and Improve Cash Control
Digital Media Technology Solutions helps finance teams assess where card fees, settlement delays and manual reconciliation are affecting EBITDA. See how our Open Banking solutions can help you receive funds faster while reducing transaction costs and simplifying payment operations. If you need a clear commercial assessment of your current payment setup, contact us to discuss the figures and integration requirements.