The Hidden Cost of Channel-by-Channel Reconciliation
Unified commerce cuts reconciliation costs by giving finance and operations teams one clear view of sales, payments, refunds, fees and settlement dates. Without it, a growing business can be taking payments through tills, ecommerce platforms, marketplaces, payment links, direct debit, bank transfer and mobile devices, while reconciling every route separately.
That fragmentation is more than an accounts problem. It affects margin, cash forecasting, stock decisions and confidence in management reporting. A small daily number of unmatched payments, duplicate refunds or settlement differences can create a steady stream of manual work. By month-end, skilled finance staff may be spending hours tracing transactions across systems rather than analysing performance.
We see this issue in businesses from £1m to £250m turnover. You do not need enterprise-scale operations to develop enterprise-scale data fragmentation. Founded in 2016 and based in London and Essex, we have helped organisations reduce overheads, modernise systems and improve margin performance through better payment processes, procurement and technology decisions.
Unified commerce is not simply another checkout tool. It is a connected environment where order, customer and payment data can be matched in one operational record. This supports faster reconciliation across card payments, bank transfers, ecommerce orders and refunds, while giving your team clearer visibility of what has settled and what needs attention.
When Unified Commerce Becomes a Finance Priority
Reconciliation problems usually build slowly. A finance team may add a spreadsheet here, a manual export there, and a month-end workaround when reports do not agree. Each step feels manageable until trading volumes rise, a new payment provider is added, or the team faces a difficult close.
Warning signs often include:
- Month-end close taking longer than it should
- Staff exporting, rekeying or merging data between systems
- Settlement totals that do not match sales reports
- More refund queries, aged debtors or payment disputes
- Channel reports showing different versions of the same transaction
October is a sensible point to review these issues. Q4 trading can quickly increase transaction volumes, especially around Black Friday and Christmas. It is also the period when many businesses begin shaping budgets, reviewing supplier renewals and planning operational priorities for the next financial year. Waiting until year-end often means carrying the same inefficient process through another trading cycle.
Changes in your business can also trigger a review. A new ecommerce platform, an additional site, marketplace expansion, a switch in payment provider, or an ERP or CRM replacement can each create another silo. We recommend treating these changes as one operational technology and systems integration decision, not a series of separate software purchases.
Why Reconciliation Leakage Depresses EBITDA
Reconciliation leakage shows up in the P and L in more places than many boards expect. The direct cost includes finance-team hours, external bookkeeping support, payment gateway charges, merchant-service fees, duplicate software subscriptions and exception handling. The indirect cost can be more damaging, because it reduces the speed and quality of commercial decisions.
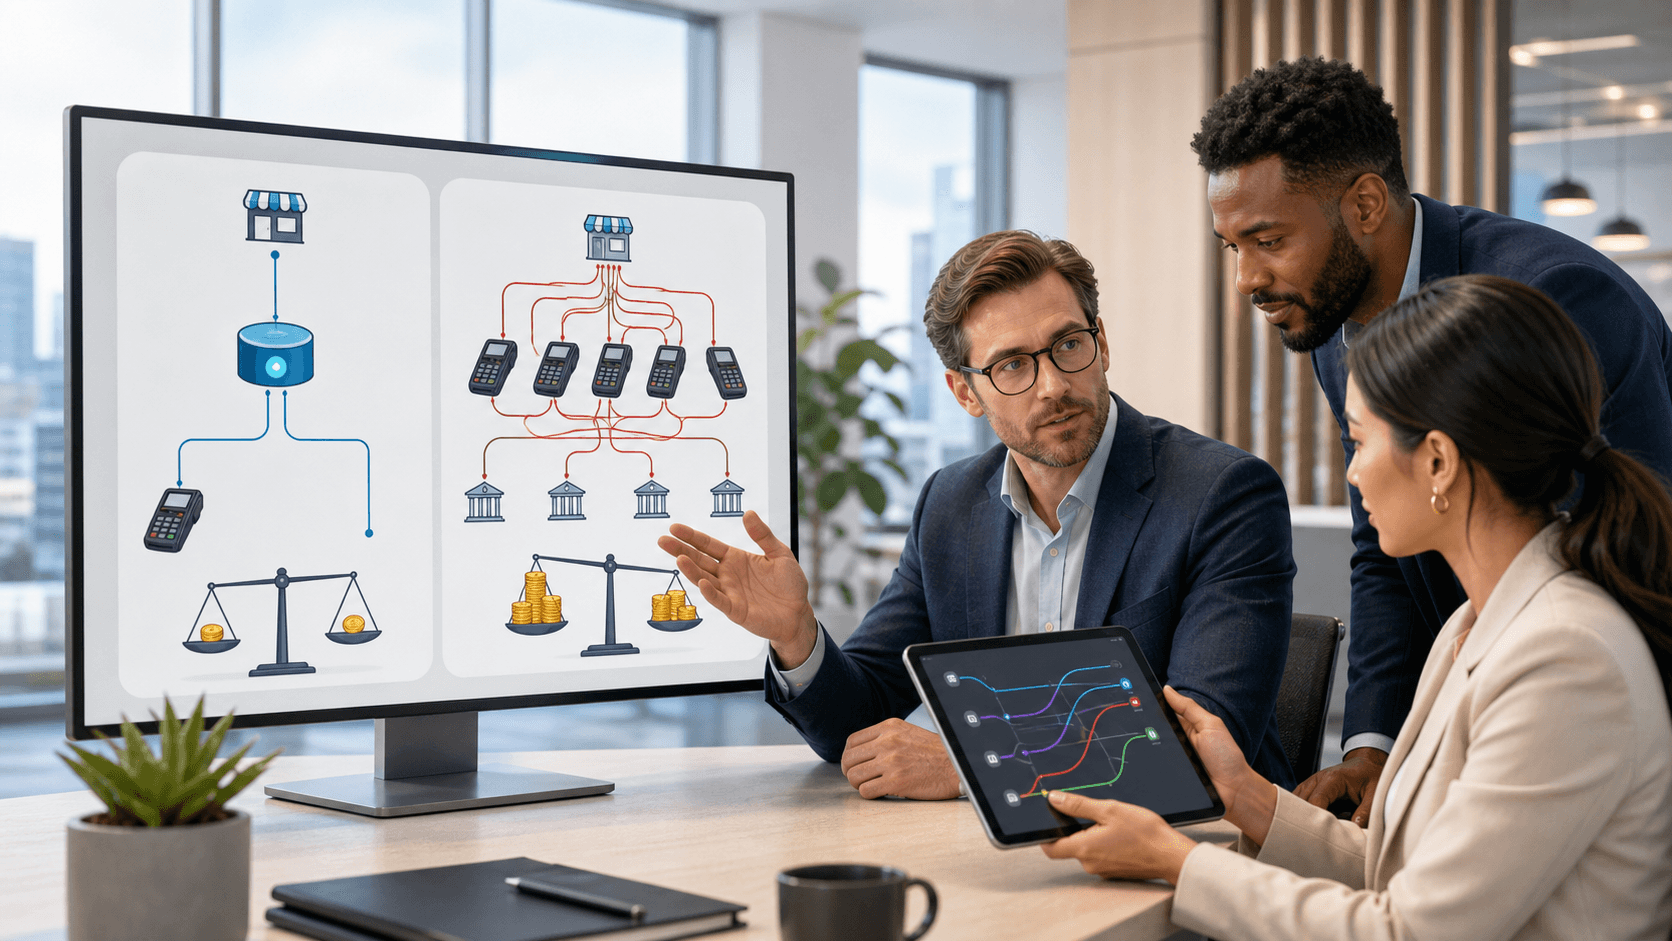
Consider a multi-site retailer or hospitality group using separate card terminals, an ecommerce gateway and bank transfer. Every week, someone may need to compare sales records with processor reports, check refunds, identify missing settlements and confirm bank receipts. When each exception takes hours rather than minutes, highly capable finance staff are tied up in administration instead of cash control, supplier analysis and margin improvement.
Payment mechanics matter here. Card payments can carry interchange fees, acquiring charges, varied settlement times and chargeback exposure. For suitable transactions, open banking can provide instant settlement, zero chargebacks and transaction fees below 1 percent. The aim is not to push every customer towards one method. It is to make sure your business can offer the lowest appropriate cost of acceptance while retaining a clear audit trail.
Alongside payment review, supplier cost benchmarking can reveal whether contracts, terminal arrangements and gateway charges still reflect your current trading profile. Small inefficiencies across several suppliers can steadily weaken EBITDA.
How Unified Commerce Creates One Financial Record
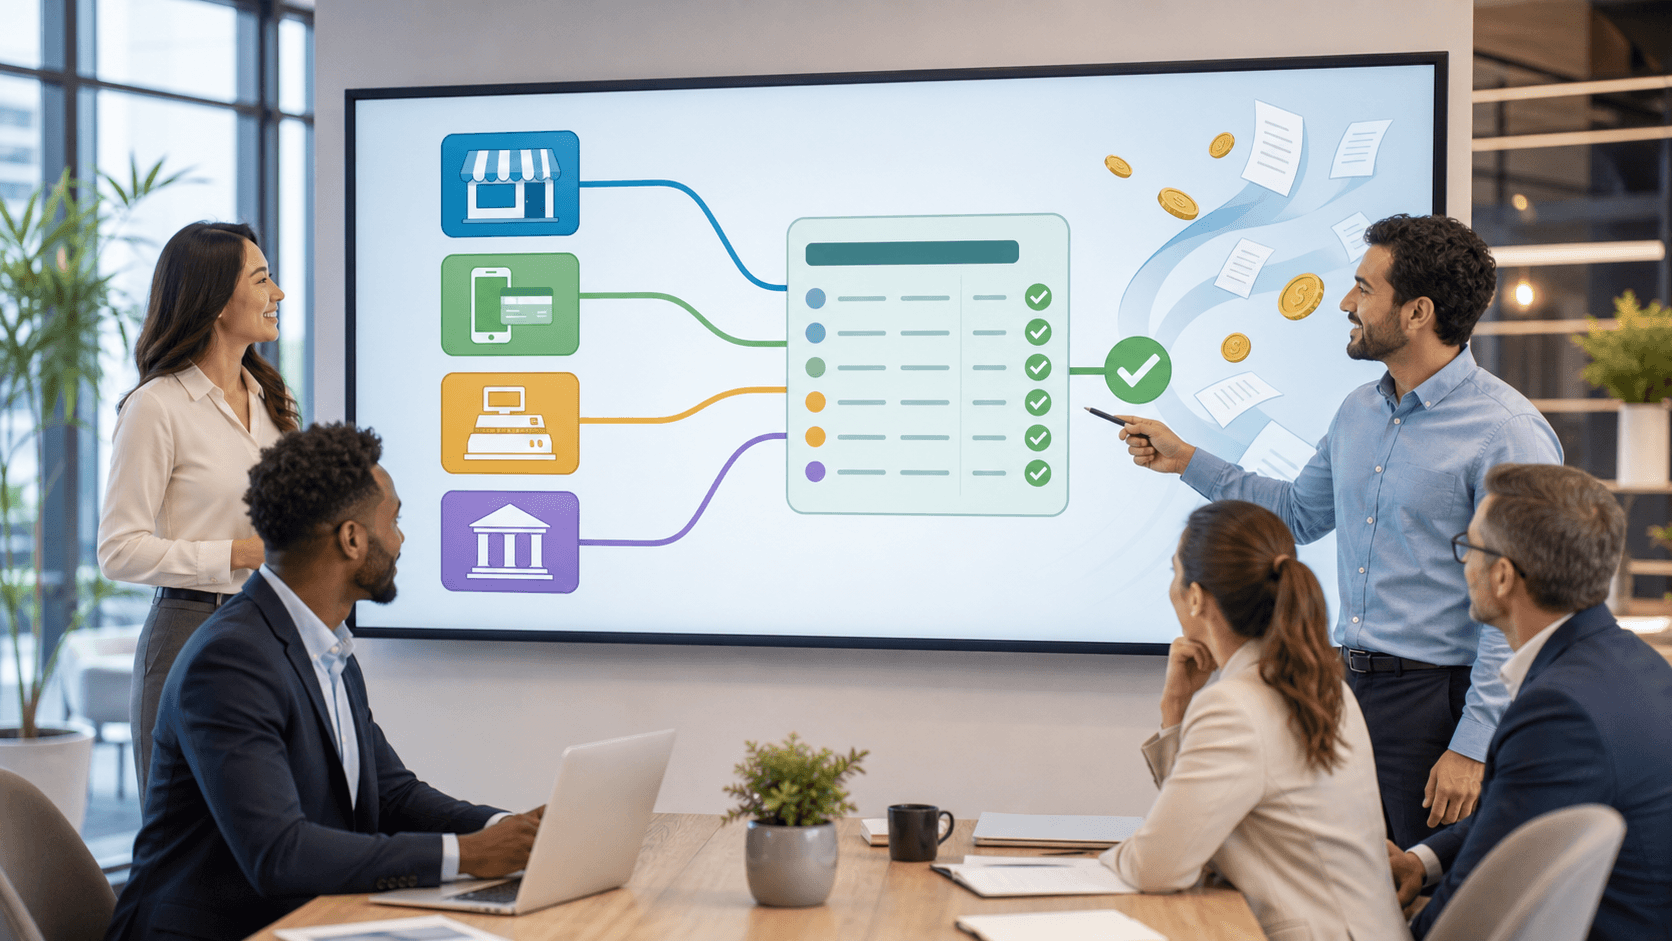
The target model is straightforward: every transaction should carry a consistent reference from sale to bank account. That reference should connect the customer, order, payment method, refund, fulfilment status, merchant fee and settlement date. Finance should not have to rely on informal staff knowledge or search through disconnected platforms to answer a basic question about a payment.
Most businesses already own much of the technology required. The issue is deciding which platform owns each data point and ensuring information moves accurately between systems. Your environment may include payment terminals, ecommerce checkout, online banking, accounting software, ERP, CRM, booking tools, stock platforms and customer-service systems. Unified commerce does not automatically mean replacing everything.
Instead, we focus on where data silos are created and where manual hand-offs cause errors. Strong controls can then be built into the operating model, including daily automated matching, exception queues, role-based refund approval and merchant-fee reporting by channel. The result is tighter control with less manual intervention, while automated operational workflows reduce the repeated admin that slows teams down.
Build a Unified Commerce Control Plan
A sensible plan begins with a full channel and cost audit. Before selecting technology, map every way customers pay and every system that records the transaction. This gives you a factual baseline rather than a supplier-led proposal.
Your audit should capture:
- Card terminals, ecommerce checkout, payment links, marketplaces, recurring payments and bank transfers
- Payment providers, fee structures, contract terms and settlement timetables
- Software used at each stage, plus the owner of each data set
- Current reconciliation steps, manual exports and unresolved exceptions
- Refund delays, chargeback ratios and the age of unreconciled items
Next, quantify the monthly labour tied up in reconciliation and compare it with merchant fees by payment type. This makes the opportunity visible to the board and allows you to judge which intervention will have the fastest payback.
In some cases, the answer is to connect existing platforms. In others, it may be sensible to consolidate providers, introduce open banking for eligible payments, automate settlement matching or replace one weak system creating disproportionate manual work. We combine technology advice with FTSE 250-level procurement leverage to reduce supplier costs and negotiate stronger commercial terms, with savings of up to 60 percent in appropriate procurement categories.
Turn Reconciliation Costs Into Margin This Quarter
Fragmented reconciliation is not an unavoidable consequence of growth. When your teams can see channels, payments, fees and settlements in one operational view, they can close faster, forecast cash with more confidence and spend more time on work that protects margin.
Before peak trading and year-end close, the practical priority is clear: identify where data breaks, who owns each exception and which payment routes create the most manual effort. A unified payment integration plan turns those answers into a cleaner financial record and a more controlled operation.
Reduce Reconciliation Costs Before They Hit Margin
Digital Media Technology Solutions can assess where fragmented payments, duplicate data and manual matching are inflating finance costs. Our unified commerce technology approach connects payment methods and operational systems to give finance a clearer, more reliable record. If you need a practical route to lower processing effort and stronger cash control, contact us to discuss the highest-value opportunities in your current setup.