Open Banking Provider Vs Card Acquirer: a CFO Fee Test
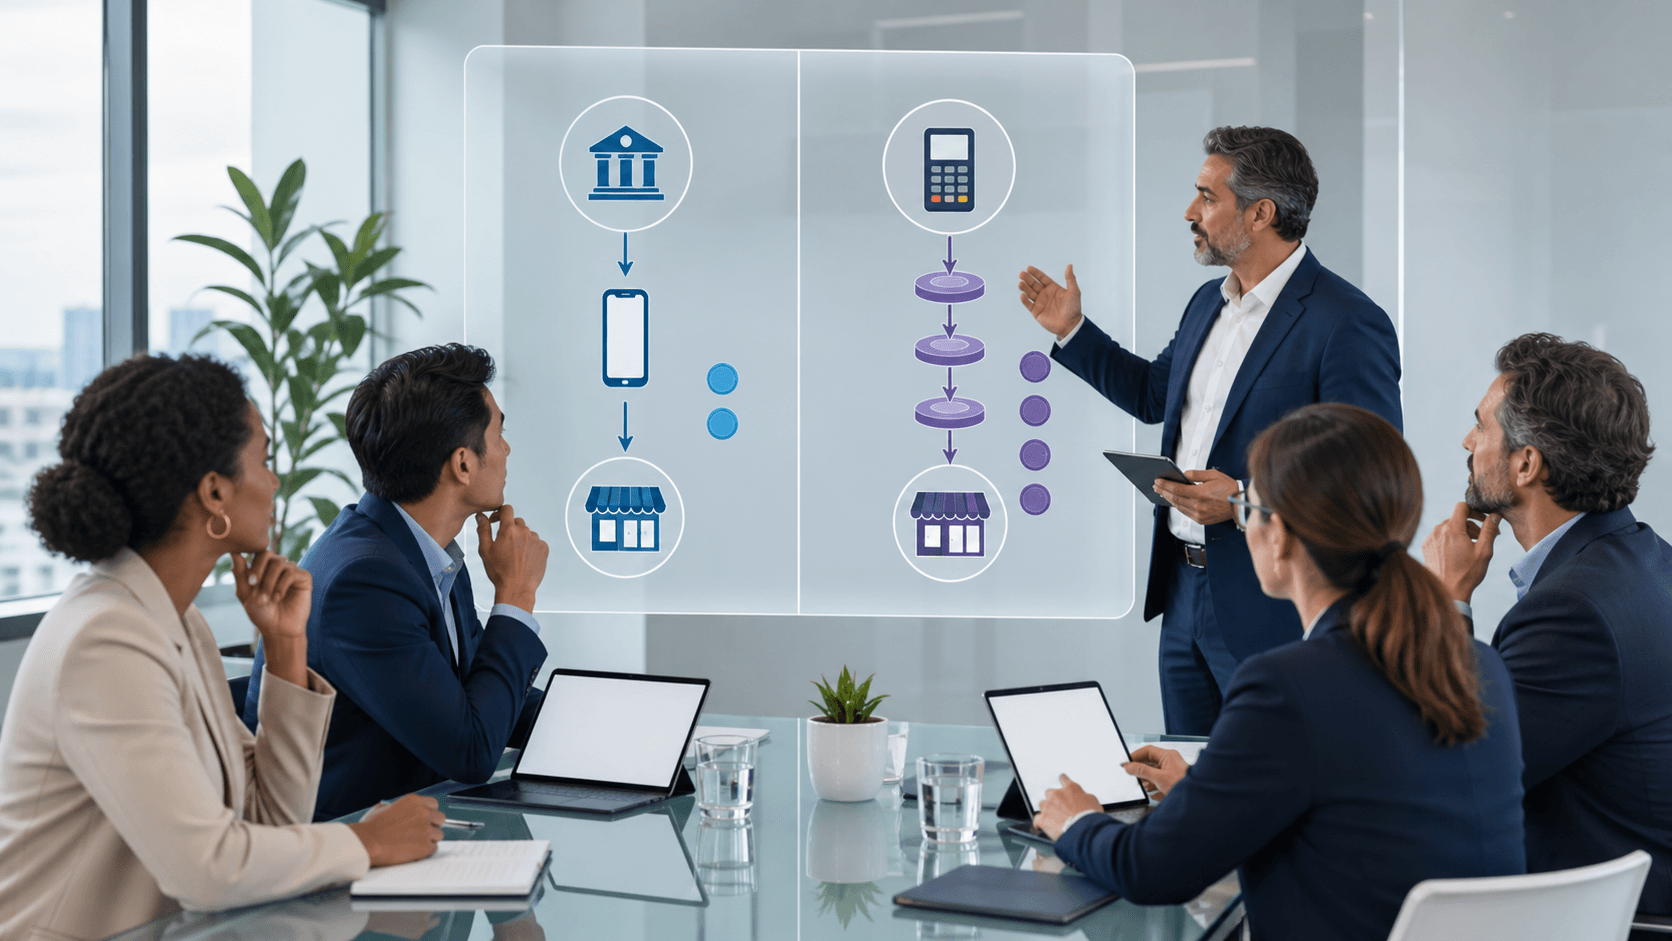
Card payments are familiar, but familiarity can be expensive. A card acquirer processes payments through card schemes, while an open banking provider enables account-to-account payments directly from a customer's bank. The CFO question is not which option is newer. It is which one delivers the lower fully loaded cost for every pound collected.
That difference matters whether you process £2 million, £10 million or £50 million a year. Small transaction costs can become a persistent P&L leak, reducing gross margin, EBITDA and available cash. Since 2016, we have helped businesses across London and Essex review procurement, payment technology and operational costs using FTSE 250-level buying leverage. The aim is simple: expose avoidable supplier spend and improve the commercial terms behind it.
Run the Fee Test Before Your Next Budget Cycle
Autumn is the right time to review payment costs before budgets, forecasts and supplier renewals become fixed. If card fees are rising alongside sales, your payment operation may be taking more from each transaction than management reporting shows.
We recommend a review when any of these events appear:
- Your card terminal, gateway or acquirer agreement is approaching renewal
- Online payment volumes or average order values are increasing
- Commercial, corporate or overseas card payments are becoming more common
- Chargeback ratios are rising, or finance teams are spending too long reconciling reports
- Margin pressure is forcing closer scrutiny of recurring operating costs
An open banking and payment processing solution should be part of that review when card fees have become a material line item. That does not mean removing cards from every checkout or payment page. Cards remain important where customer preference and conversion demand them. Instead, we assess which payment journeys could move to account-to-account payments without creating friction for customers or extra work for your team.
See Where Card Acquiring Inflates Your Cost Base
The merchant service rate on an acquirer quote is rarely the whole story. A CFO fee test needs to measure the true effective cost of accepting cards, not just the percentage shown at the top of a proposal.
Our reviews look beyond the headline rate to include interchange fees, card-scheme fees, acquirer margin, authorisation charges, gateway fees, terminal rental, PCI compliance costs, chargeback administration and internal reconciliation time. Each cost may look modest on its own. Together, they can create a much higher unit cost than the one used in management accounts.
Transaction type matters too. Domestic consumer debit cards, consumer credit cards, premium cards, commercial cards, corporate cards and non-UK cards can all carry different economics. A blended rate can hide the payment types that are quietly eroding margin.
In practice, we often see multi-site service businesses reporting the advertised rate while fixed terminal charges, gateway costs and finance administration sit elsewhere in the P&L. The result is a distorted view of payment profitability. We benchmark supplier agreements, transaction mix and collection processes so you can see the real cost per collected pound.
Decide Where an Open Banking Provider Wins
Account-to-account payments can produce a stronger result in the right situations. An open banking provider may offer sub-1% transaction fees, fast settlement and no card-scheme chargeback mechanism. This can make a meaningful difference for higher-value payments, invoice settlement, deposits, repeat B2B collections and payment links.
The balanced view is important. Open banking is not automatically the best answer for every sale. Before changing a payment journey, we consider:
- Whether customers are likely to choose the payment method
- How refunds and customer service requests will be managed
- Fraud controls and payment authorisation processes
- Integration effort, reporting requirements and settlement timing
- Where retaining card payments protects conversion
No card-scheme chargeback process does not mean no payment risk. You still need clear refund rules, effective fraud controls and a reliable route for customer support. Good payment design protects revenue as well as reducing fees. The objective is to remove unnecessary card-scheme costs without weakening trust or creating avoidable exceptions for operations.
Build a Blended Payment Stack That Protects Margin
A forced migration from cards to open banking is rarely the right commercial decision. The stronger approach is a blended payment stack, keeping card acceptance where it supports customer choice and directing suitable transactions towards lower-cost account-to-account collection.
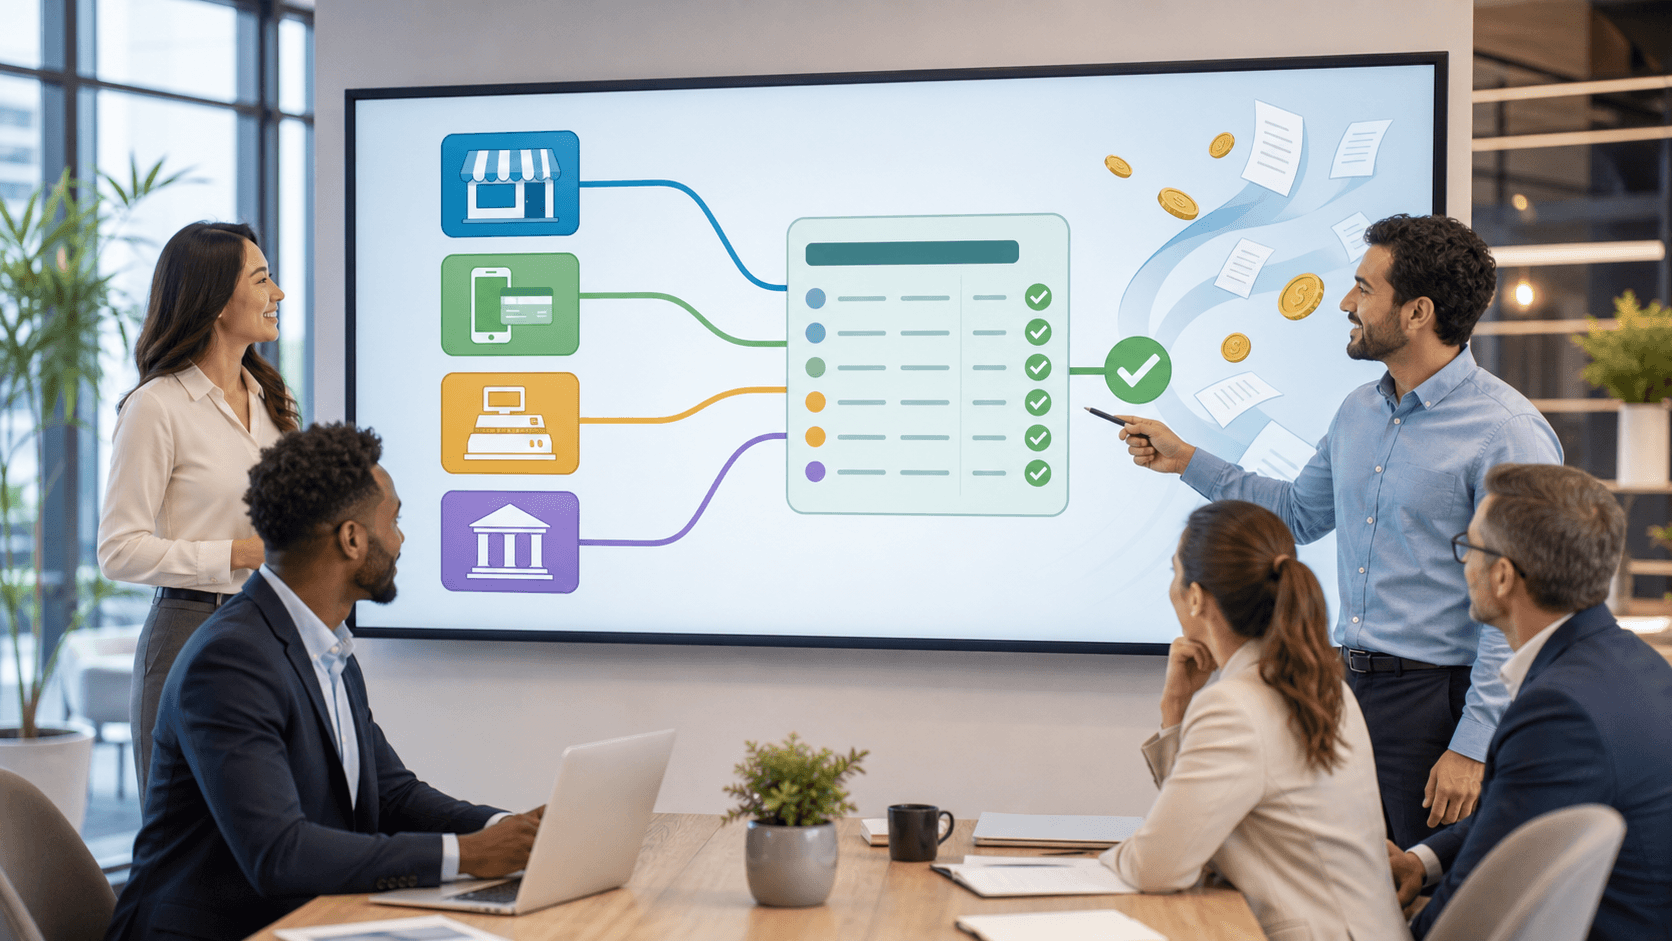
We use a practical four-step review:
- Export 12 months of transactions by channel, card type, payment value and customer segment.
- Calculate the effective cost of card acceptance, including supplier fees and internal administration.
- Identify payment journeys suited to account-to-account payments, such as booking deposits, invoice pages, trade account settlements and larger online purchases.
- Model likely savings alongside conversion impact, implementation work and operational change.
A single integration that brings together multiple payment methods can also reduce fragmented reporting. For an Ops Director, that can mean fewer manual exceptions and less time spent matching payment records. For a CFO, it means clearer cash visibility, tighter control over collection costs and less supplier creep hidden in separate invoices.
Complete a CFO Payment Cost Review Before Commitments Are Fixed
Before approving another budget or renewing a merchant services agreement, test the numbers behind the rate. Review acquirer statements, merchant service agreements, terminal and gateway charges, transaction mix and the payment journeys your customers actually use. Then compare those findings with the realistic role an open banking provider could play.
The goal is not change for its own sake. It is to reduce avoidable transaction costs, protect EBITDA, improve cash flow and build a payment operation that supports growth without adding unnecessary overhead.
Turn Payment Fees Into Margin Headroom
Our open banking provider service helps finance teams assess transaction economics, settlement speed and integration requirements against their current acquiring model. Digital Media Technology Solutions brings procurement discipline to payment costs, identifying where fee structures and operational friction are eroding margin. If you need a CFO-level review of your payment operation, contact us to discuss the numbers and the practical next steps.