Payment costs can quietly eat into margin long before they appear as a major line on a management report. The visible merchant service charge is only part of the picture. Interchange fees, scheme fees, gateway charges, terminal rental, PCI compliance, foreign exchange mark-ups, failed-payment administration and chargeback exposure can sit across several suppliers.
We see this as a profit and loss issue, not simply a banking or IT decision. When sales grow, payment costs can rise faster than revenue if contracts, transaction routing and settlement terms are left untouched. Since founding Digital Media Technology Solutions in 2016, we have brought procurement, payment technology and operational improvement together for businesses across London and Essex, using FTSE 250-level procurement leverage to expose avoidable spend.
Turn Payment Costs Into Margin Recovery
Fragmented arrangements make it difficult to see the true cost of taking money from customers. One supplier may provide terminals, another the acquiring service, another the gateway, while finance teams manually chase settlement reports and reconcile exceptions. Each piece can look reasonable on its own. Together, they may create unnecessary operating expenditure and weak cash visibility.
A structured payments procurement review identifies where margin is leaking through:
- Higher effective transaction costs by card type, channel or location
- Slow settlement cycles that delay access to cleared funds
- Duplicate technology, minimum fees and overlapping supplier contracts
- Manual reconciliation work that takes time away from finance control
- Chargeback handling and failed-payment processes with unclear ownership
Our payment processing solutions focus on the full commercial and operational picture. The goal is not to change providers for the sake of it. It is to establish whether your current estate gives you appropriate unit costs, useful reporting, predictable settlement and a clear owner for every moving part.
When Payments Procurement Demands Board Attention
Contract renewal dates are the obvious trigger, but they should not be the only one. We recommend reviewing terminal, acquiring, gateway and banking agreements around 90 to 180 days before renewal. That window gives you time to understand notice periods, benchmark terms and negotiate from a position of control rather than urgency.
October is a sensible point to put payments procurement on the board agenda. Fourth-quarter planning brings annual budgets, EBITDA targets, supplier rationalisation and peak trading into sharp focus. For retail, hospitality, e-commerce and service businesses, higher transaction volumes can magnify every avoidable basis point. For B2B firms, year-end collection targets make settlement speed and acceptance costs just as important.
Operational changes can also expose a need for a review. We often see payment estates become harder to manage after growth or system change, including:
- Rising card acceptance fees or chargeback ratios
- Several payment providers with inconsistent reports
- Manual reconciliation and delayed settlement data
- New sites, online channels or international trading activity
- Mergers, acquisitions or ERP replacements creating duplicate contracts
Payments procurement and cost reduction deserve board attention when you cannot connect payment costs to revenue, customer payment methods or individual locations. If finance cannot measure the full cost of accepting money, that is a control risk as well as a margin risk.
Why Payments Procurement Has Become an EBITDA Lever
Finance teams already apply commercial discipline to energy, telecoms, insurance and other material operating costs. Payments should receive the same treatment. The headline rate on a proposal rarely tells the whole story. Total card acceptance cost can include interchange, scheme fees, acquirer margin, authorisation charges, gateway fees, terminal rental and cross-border charges.
Blended pricing can make this especially difficult to assess. It may hide the different costs of premium cards, commercial cards and international transactions. Without transaction-level analysis, you may be comparing offers that appear similar but deliver very different outcomes for EBITDA.
Payment method mix matters too. Cards will remain important for convenience, online conversion and recurring payments. Yet higher-value invoices, deposits, B2B collections and selected online journeys may suit open banking payments. In the right use cases, these bank-to-bank payments can provide sub-1% transaction fees, instant settlement and zero chargebacks because the payment is not processed through card schemes. Customer behaviour, transaction value, channel and integration needs must always guide the decision.
An anonymised pattern is common: a multi-site business has fees spread across several contracts while finance staff reconcile settlements from different providers every day. A single review can reveal unit-cost opportunities, remove duplicate technology and give leaders clearer daily cash visibility. No outcome should be assumed, but the opportunity is often hidden in plain sight.
The same applies to operational technology solutions. Multiple acquirers, terminals, gateways and finance systems can create disconnected data, unclear ownership and avoidable administration. Better payment information supports better cash forecasting.
How to Audit Every Payment Cost and Risk
A proper audit starts with evidence, not assumptions. We take a practical, step-by-step approach that combines commercial terms with operational reality.
- Build a full supplier register. Include acquirers, payment service providers, gateways, terminal suppliers, open banking providers, foreign exchange partners, fraud tools and reconciliation software. Record end dates, notice periods, minimum fees, hardware commitments and service-level obligations.
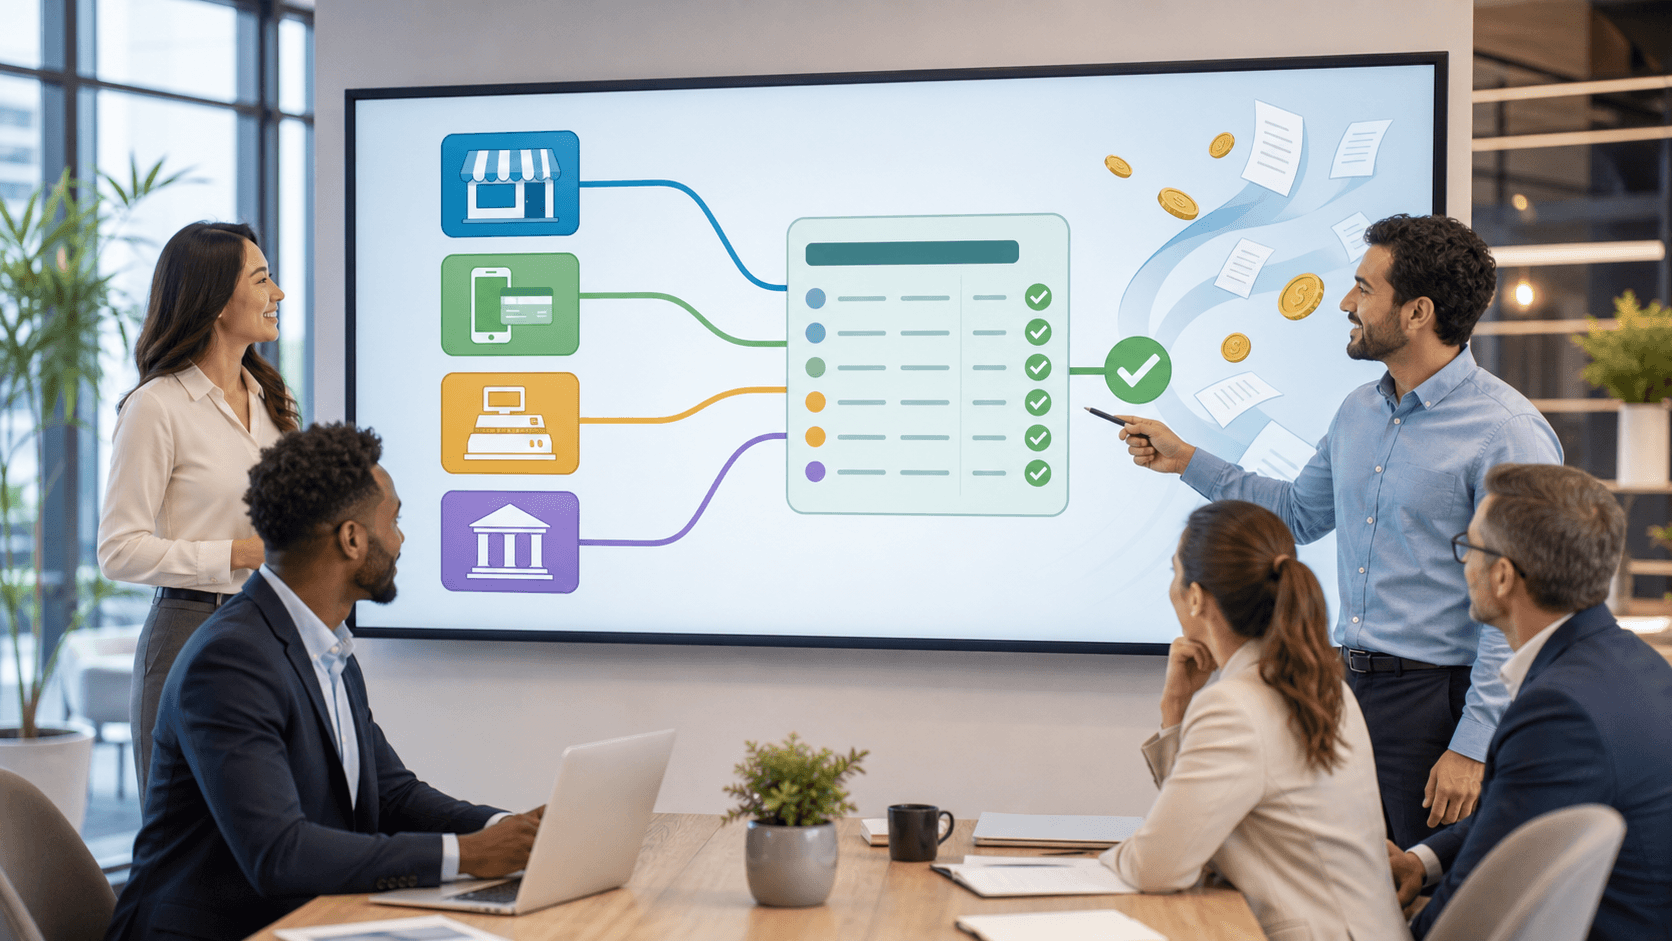
- Reconcile invoices against transaction data. Separate fixed and variable charges, then calculate the effective cost of acceptance by payment method, sales channel, location and average transaction value. Look beyond processor margin to interchange, scheme fees, refund charges, chargeback fees and costs that do not move directly with revenue.
- Map the payment-to-bank process. Track the route from customer payment to cleared funds. Settlement timing, manual reconciliation steps, data hand-offs and exceptions often reveal whether apparent savings are being lost elsewhere through administration or delayed cash.
- Benchmark the commercial and technology position. Compare current arrangements with suitable alternatives, such as consolidated acquiring, integrated methods and open banking for relevant payment journeys. Supplier benchmarking should reduce total cost, supplier risk and operational friction, not simply replace every provider.
Our FTSE 250-scale buying power can produce savings of up to 60% in appropriate procurement categories. Payment outcomes, however, must be assessed against your own transaction profile, customer needs and contractual position.
Design a Lower-Cost Payment Model This Quarter
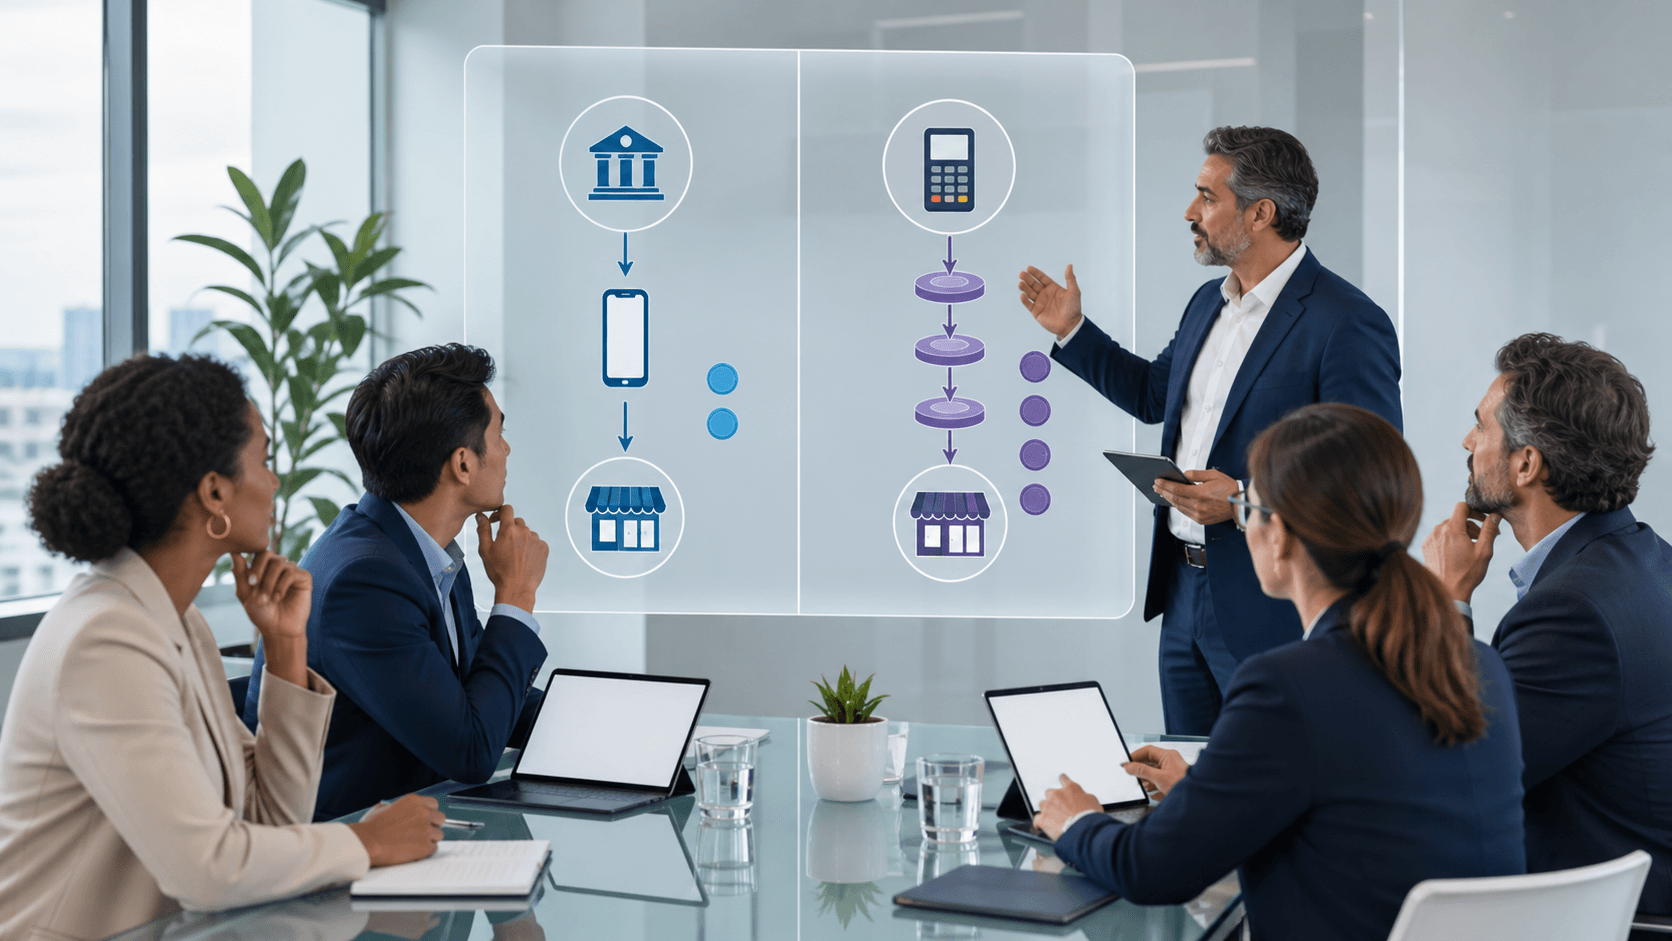
The best model is rarely one payment method or one supplier. Cards may remain the right choice for quick customer decisions and familiar checkout experiences. Meanwhile, open banking may be better suited to selected invoices, deposits and B2B collections where faster settlement and lower acceptance costs matter most.
A single integration that unifies more than 100 payment methods can also reduce friction behind the scenes. The finance benefit is not technical simplicity alone. Consistent settlement data, consolidated reporting and fewer supplier hand-offs can reduce manual work and improve management information. CRM and automation integration can help teams see where payment failures happen and how much time is being spent resolving exceptions. Payment terminal procurement should also sit within the same review, rather than being treated as an isolated hardware decision.
Before prioritising any change, measure it against four tests: does it lower total cost of acceptance, improve cash conversion, reduce finance administration or strengthen supplier control? October is the right time to establish that baseline before year-end budgeting, peak trading and next-year negotiations make fragmented payment arrangements harder to unwind.
Reduce Payment Costs Without Adding Complexity
Digital Media Technology Solutions helps finance teams identify where fees, settlement delays and fragmented supplier arrangements are eroding margin. Our payments procurement specialists assess the commercial and operational case for change, from transaction costs to supplier control. To discuss your current payment arrangements and priorities, contact us for a focused review.